Secured Debt Any For Bad Credit In Maryland
Description
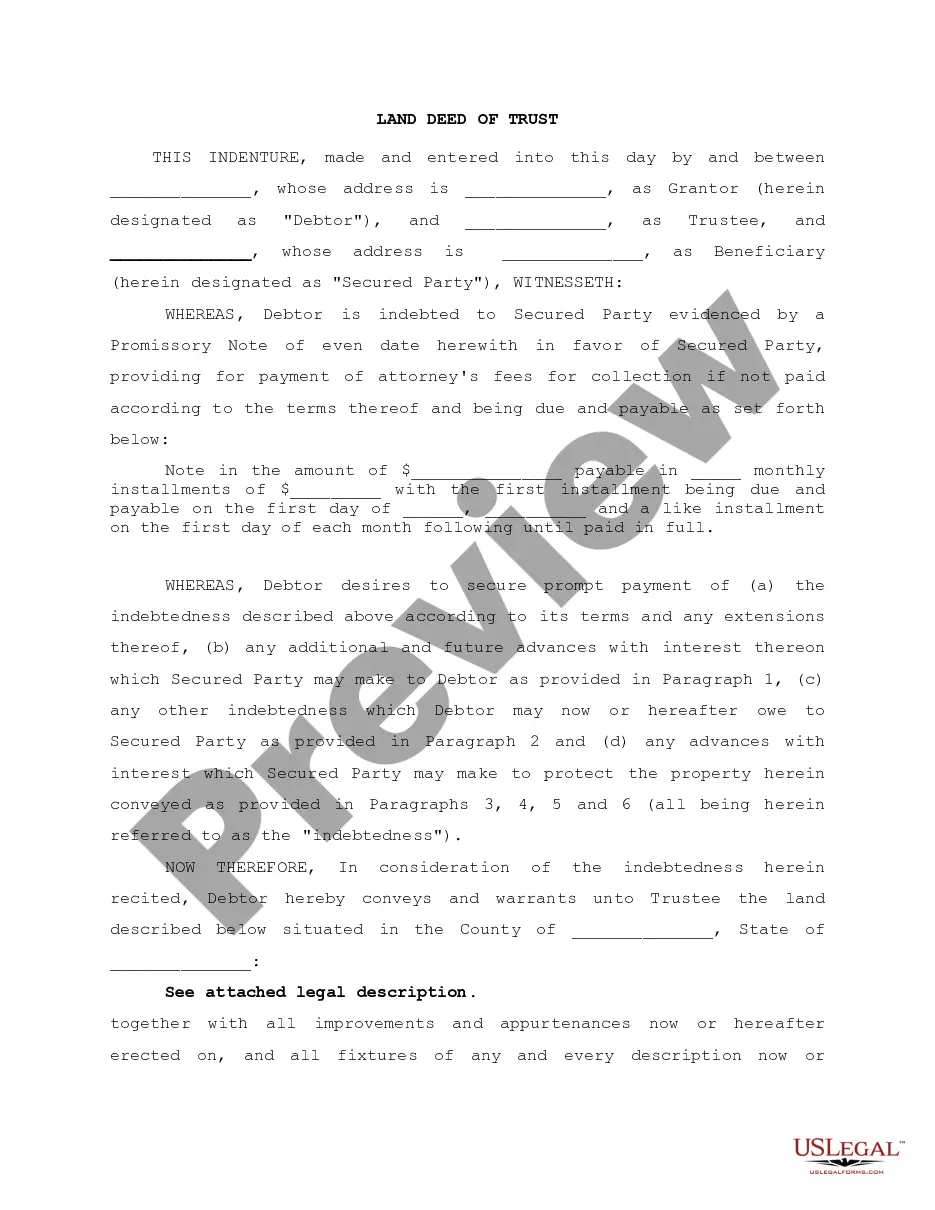
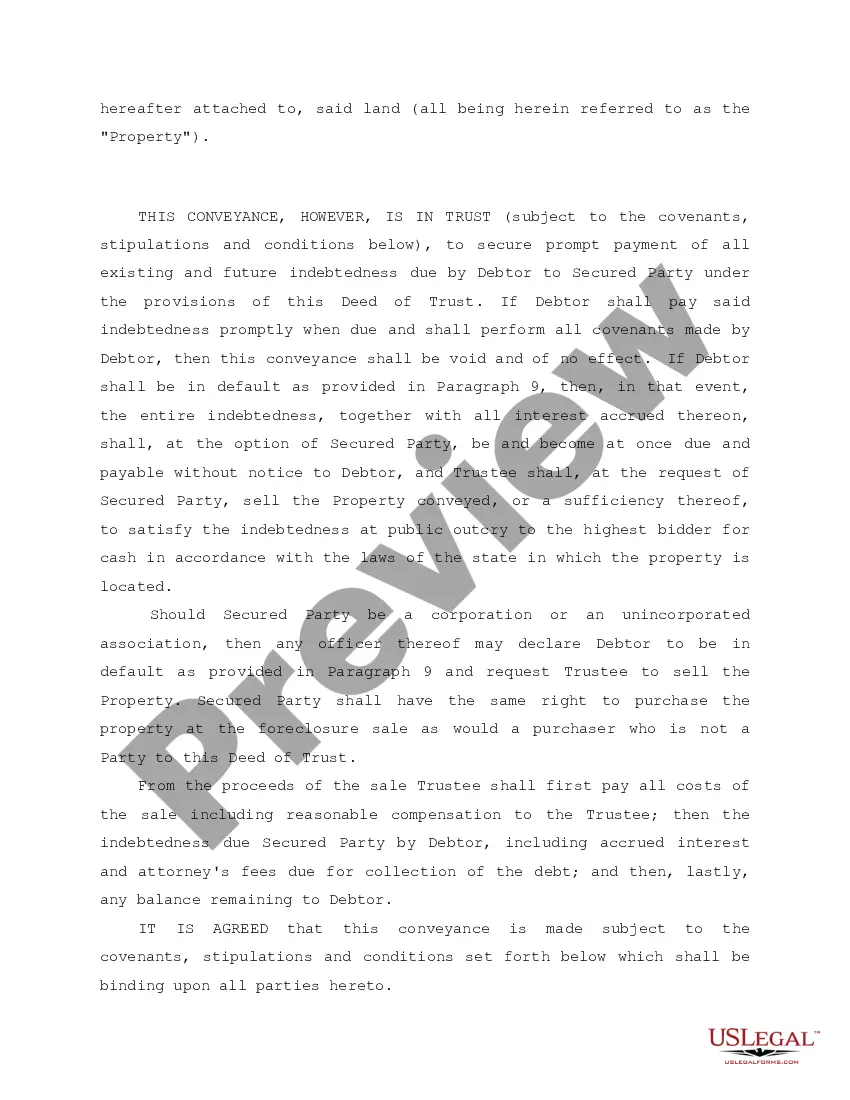
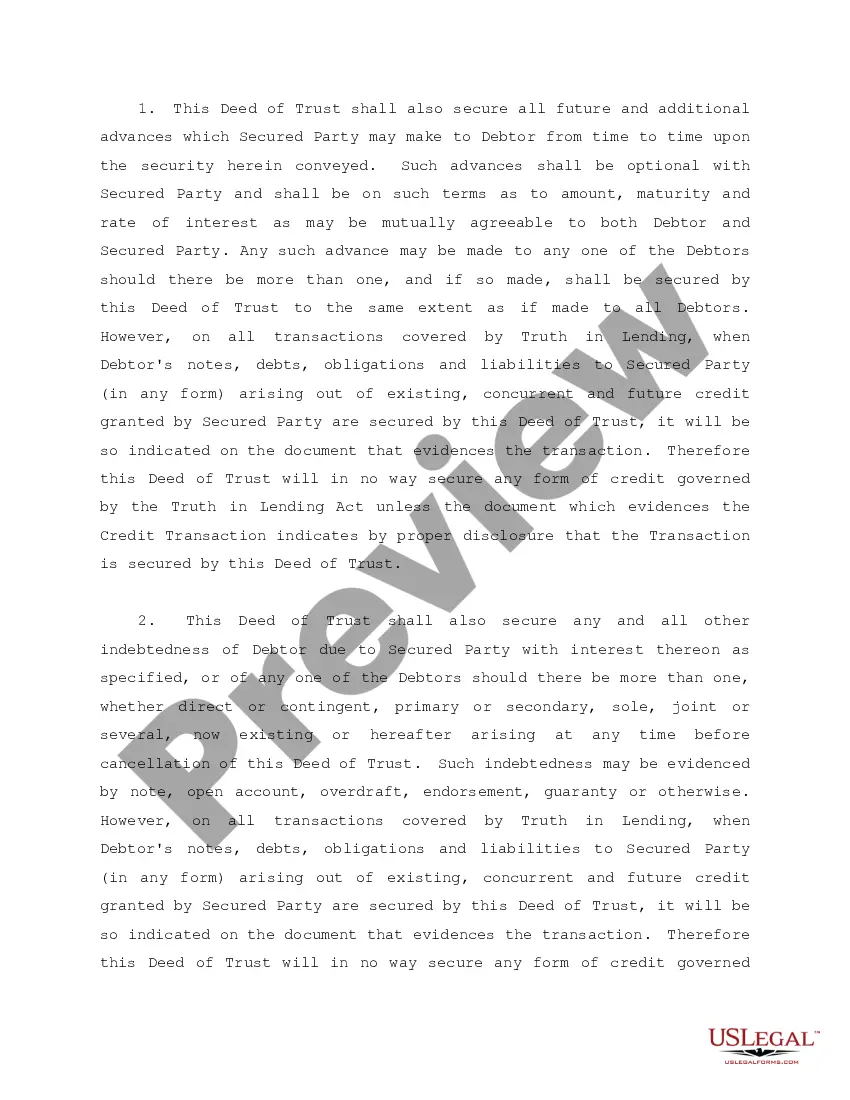
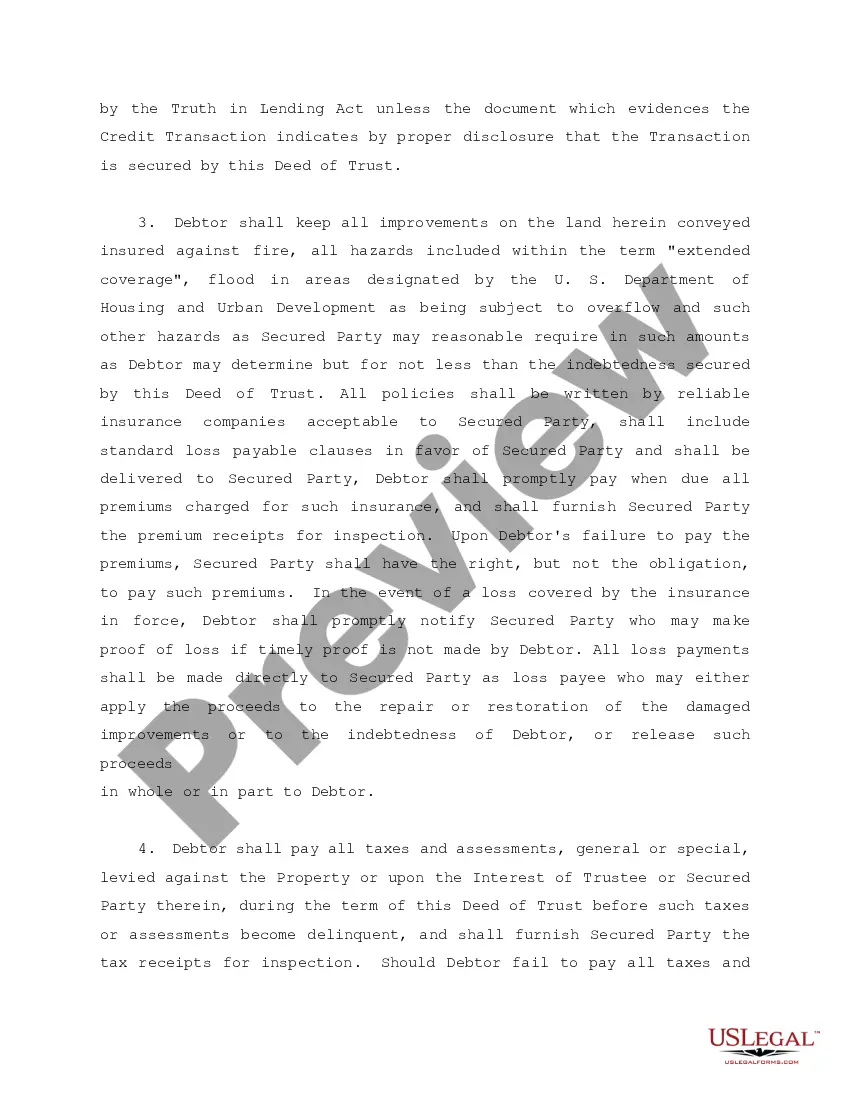
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Debt Collection Statute of Limitations by State StateWritten ContractOpen-Ended Accounts California 4 years 4 years Colorado 3 (6 most debts; rent) (2 tortious breach) 6 years Connecticut 6 years 6 years Delaware 3 years 3 years47 more rows •
3-year limit on lawsuits for debts To get a judgment, a creditor must bring the claim to court within 3 years after the debt comes due.
Yes. There are time limits governing when a creditor can sue you for a debt. These laws are called the statute of limitations. In Maryland, the statute of limitations requires that a lawsuit be filed within three years for written contracts, and 3 years for open accounts, such as credit cards.
The amount of time that a debt collector can legally pursue old debt varies by state and type of debt but can range between three and 20 years. Each state has its own statute of limitations on debt, and after the statute of limitations has expired, a debt collector can no longer sue you in court for repayment.
Yes. There are time limits governing when a creditor can sue you for a debt. These laws are called the statute of limitations. In Maryland, the statute of limitations requires that a lawsuit be filed within three years for written contracts, and 3 years for open accounts, such as credit cards.
Strategies like debt management plans, alternative consolidation loans and even debt settlement programs provide relief tailored to those with low credit scores. While each option has its pros and cons, the key is to choose the one that aligns with your financial situation and long-term goals.
Statute of Limitations in Maryland The statute of limitations allows a creditor three years to collect on debts.
Statute of limitations on debt for all states StateWrittenOral Maryland 3 years 3 Massachusetts 6 years 6 Michigan 6 years 6 Minnesota 6 years 646 more rows •
If your total monthly income over the course of the next 60 months is less than $7,475 then you pass the means test and you may file a Chapter 7 bankruptcy. If it is over $12,475 then you fail the means test and don't have the option of filing Chapter 7.