Personal Property For Insurance In New York
Description
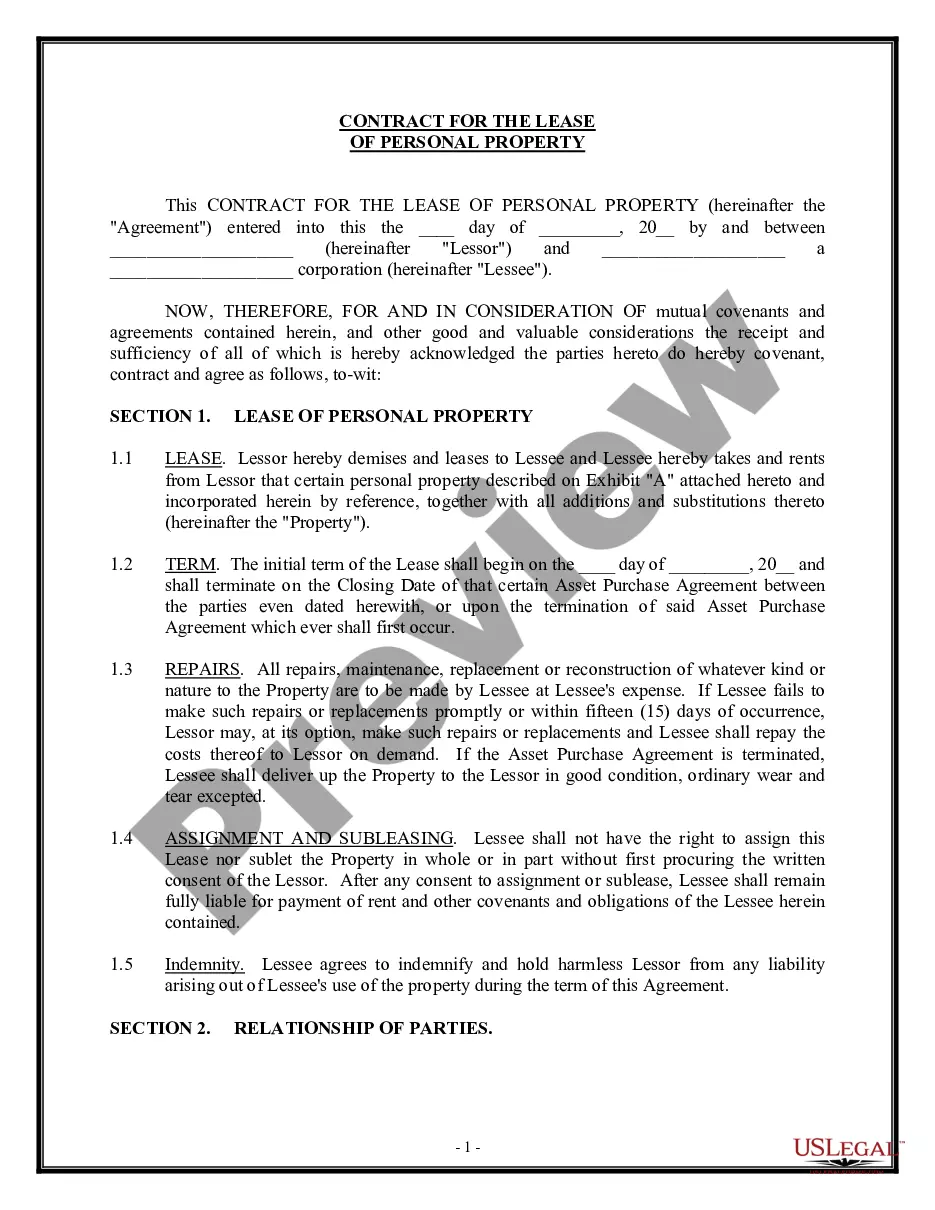
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
The sum of the value of all your items is how much coverage you need. Often, the amount of personal property coverage is determined by using 50% of your dwelling coverage limit.
Personal property is any movable property that is not permanently attached to real estate. This includes furniture, appliances, and vehicles. For landlords, it's essential to understand personal property so you can adequately protect your real estate investment.
If you are injured in a motor vehicle accident, file a written notice of claim with the No-Fault insurer that identify the injured person(s), along with reasonably obtainable information regarding the time, place and circumstances of the accident, as soon as reasonably practicable, but in no event more than 30 calendar ...
Your homeowners insurance policy will typically include some percentage – such as 50% -- of your dwelling coverage for personal property coverage. For example, if your policy's dwelling limit is $200,000, you'll have $100,000 in personal property insurance coverage.
How much BPP coverage do you need? For business property insurance policies, you typically need a policy limit of at least 80% or 90% of the value of the covered property. This is spelled out in what's called the “coinsurance provision,” which you can find in your policy declarations.
The sum of the value of all your items is how much coverage you need. Often, the amount of personal property coverage is determined by using 50% of your dwelling coverage limit. For example, if your dwelling coverage is $400,000, you'll have $200,000 in personal property coverage.
The sum of the value of all your items is how much coverage you need. Often, the amount of personal property coverage is determined by using 50% of your dwelling coverage limit. For example, if your dwelling coverage is $400,000, you'll have $200,000 in personal property coverage.
What is personal property insurance? Personal property coverage can cover your belongings such as furniture, clothing, sporting goods or electronics in the event of a covered loss. You can protect what you own whether items get damaged at your home, an apartment or anywhere in the world.
Scheduled personal property is a supplemental insurance policy that extends coverage beyond the standard protection provided in a homeowners' insurance policy. By purchasing a scheduled personal property policy, owners can ensure full coverage of expensive items, such as jewelry, in the event of a claim.
Personal property insurance is an important protection to have for your most valued possessions. Whether you live in a condo, a house or an apartment, you can get more peace of mind with the right personal property insurance.