Personal Property For Home Insurance Coverage In Maricopa
Description
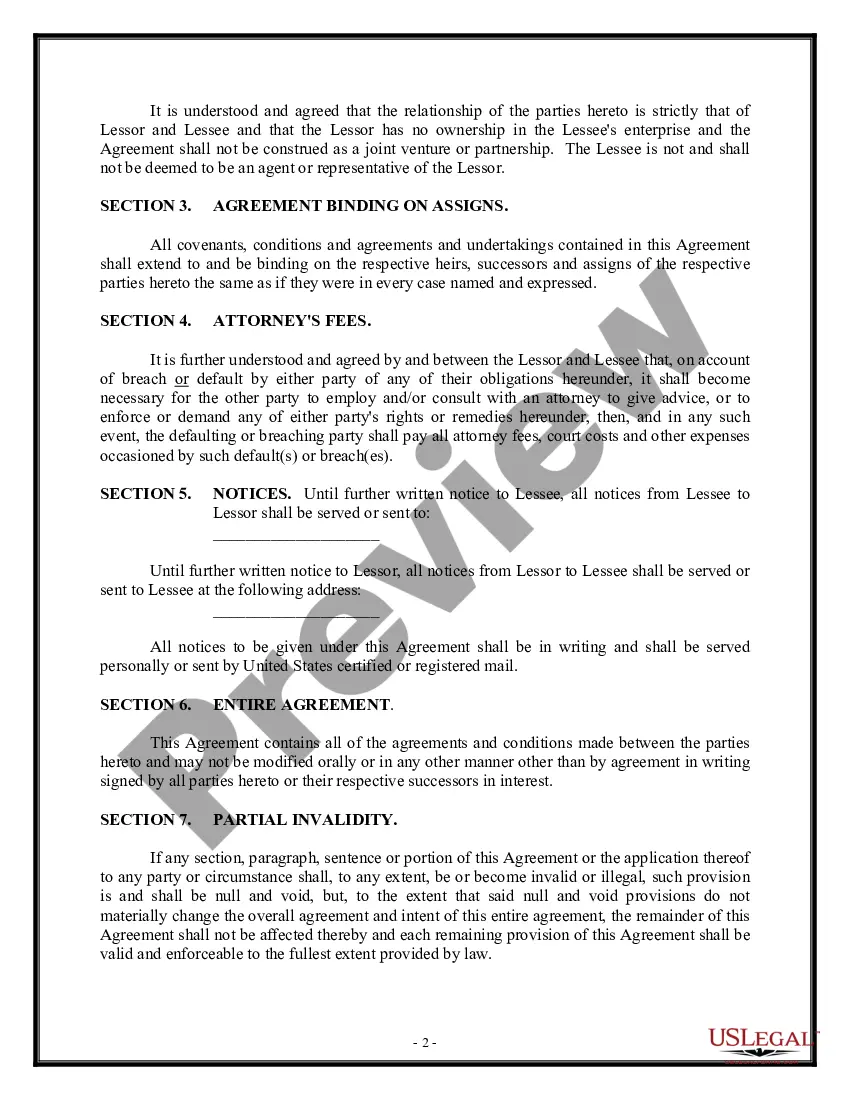
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
What Is Special Personal Property? Also known as open peril coverage, special personal property endorsement covers your home from all perils except those mentioned as exclusions. It provides wider coverage than the standard home insurance policy.
Homeowners insurance does not cover every type of stolen property. For example, it may not cover expensive jewelry. The value of the jewelry could be too much for the insurance plan.
The sum of the value of all your items is how much coverage you need. Often, the amount of personal property coverage is determined by using 50% of your dwelling coverage limit. For example, if your dwelling coverage is $400,000, you'll have $200,000 in personal property coverage.
Most home insurance providers (us included!) require you to carry a minimum amount of personal property coverage – usually around 10% of your dwelling coverage. This means a home that costs $300,000 to rebuild, typically needs a minimum of $30,000 in personal property coverage. But again – that's just a minimum.
Personal property includes things like furniture, clothing, electronics, and kitchenware.
Scheduled personal property is a supplemental insurance policy that extends coverage beyond the standard protection provided in a homeowners' insurance policy. By purchasing a scheduled personal property policy, owners can ensure full coverage of expensive items, such as jewelry, in the event of a claim.
Classifications Intangible. Tangible. Other distinctions.
Scheduled personal property is a supplemental insurance policy that extends coverage beyond the standard protection provided in a homeowners' insurance policy. By purchasing a scheduled personal property policy, owners can ensure full coverage of expensive items, such as jewelry, in the event of a claim.
Personal property listed on a scheduled endorsement is usually protected by the same perils as the base homeowners insurance policy, and often additional perils like loss or damage. These included perils are usually things like fire, theft, vandalism, and water damage, among others.