Loan Agreement Form Download With Collateral Philippines In Cuyahoga
Description
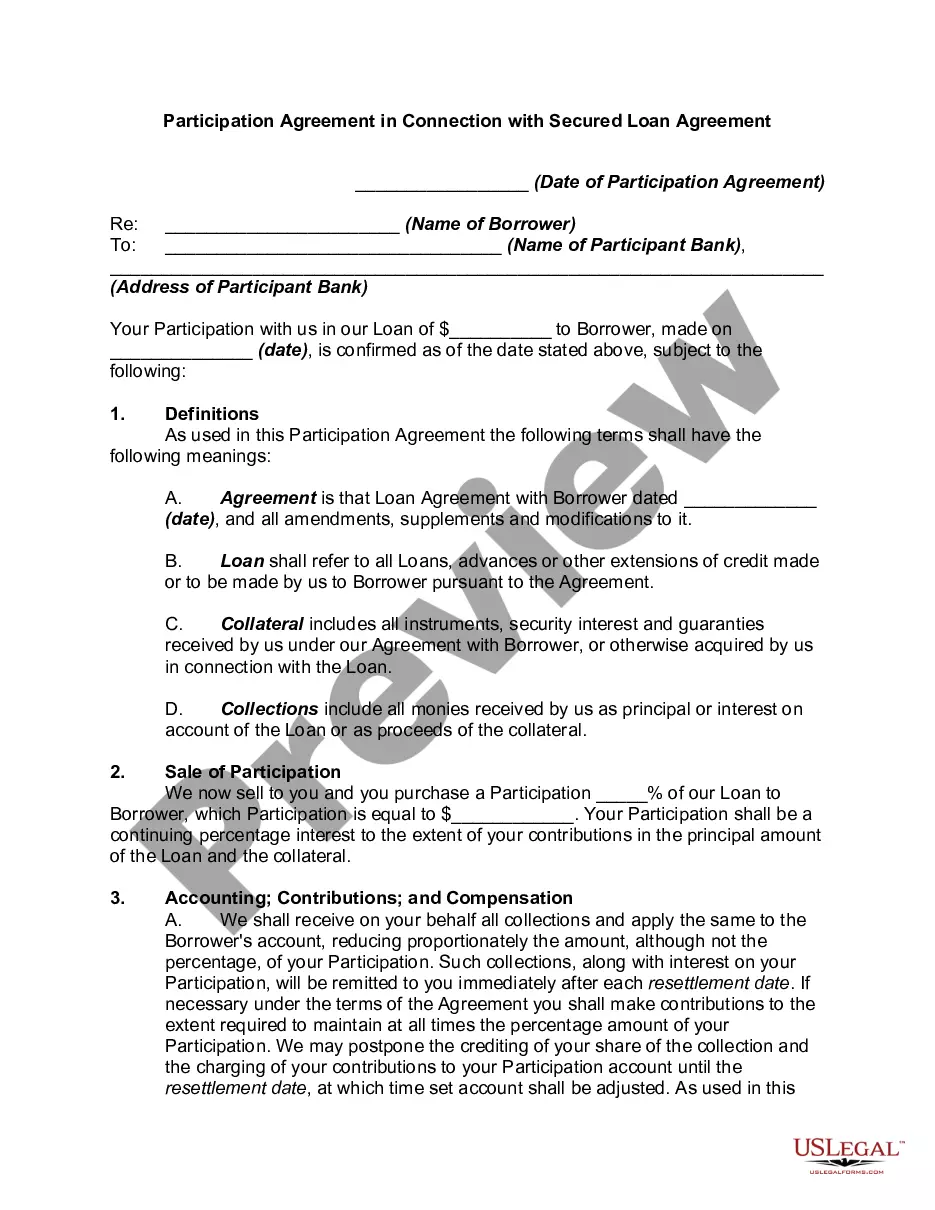
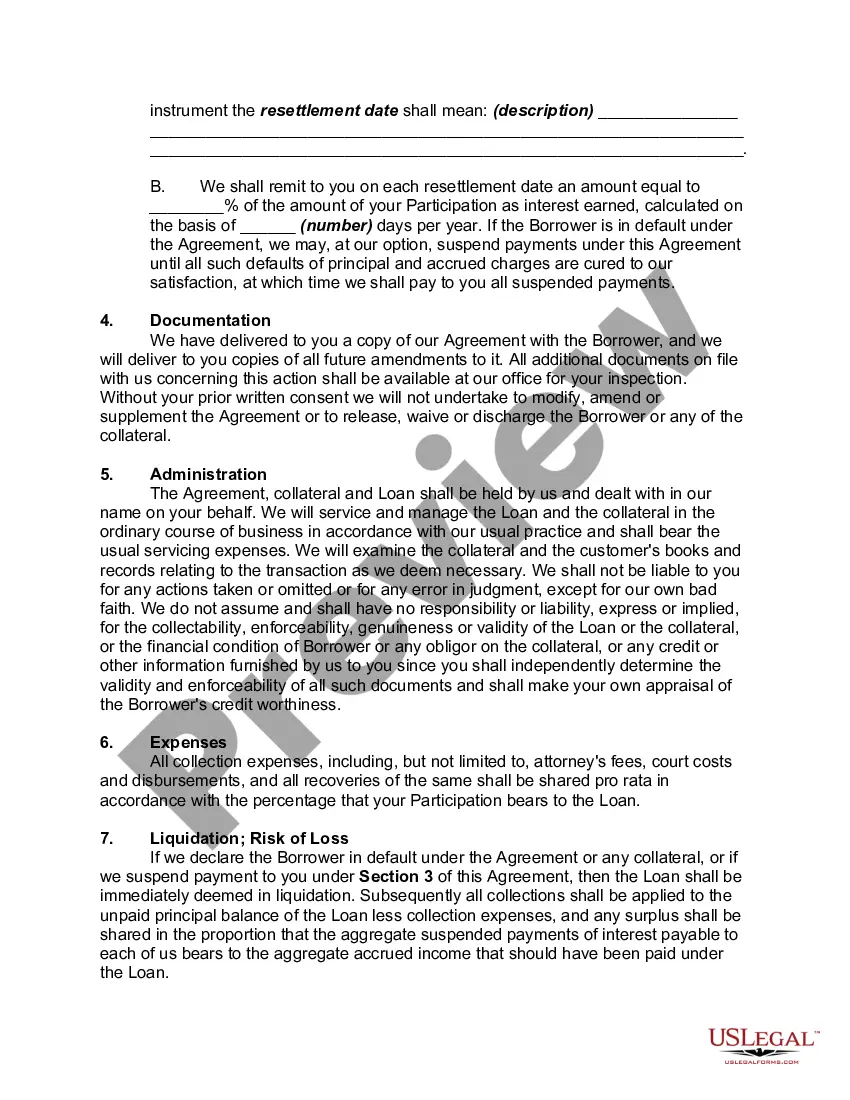
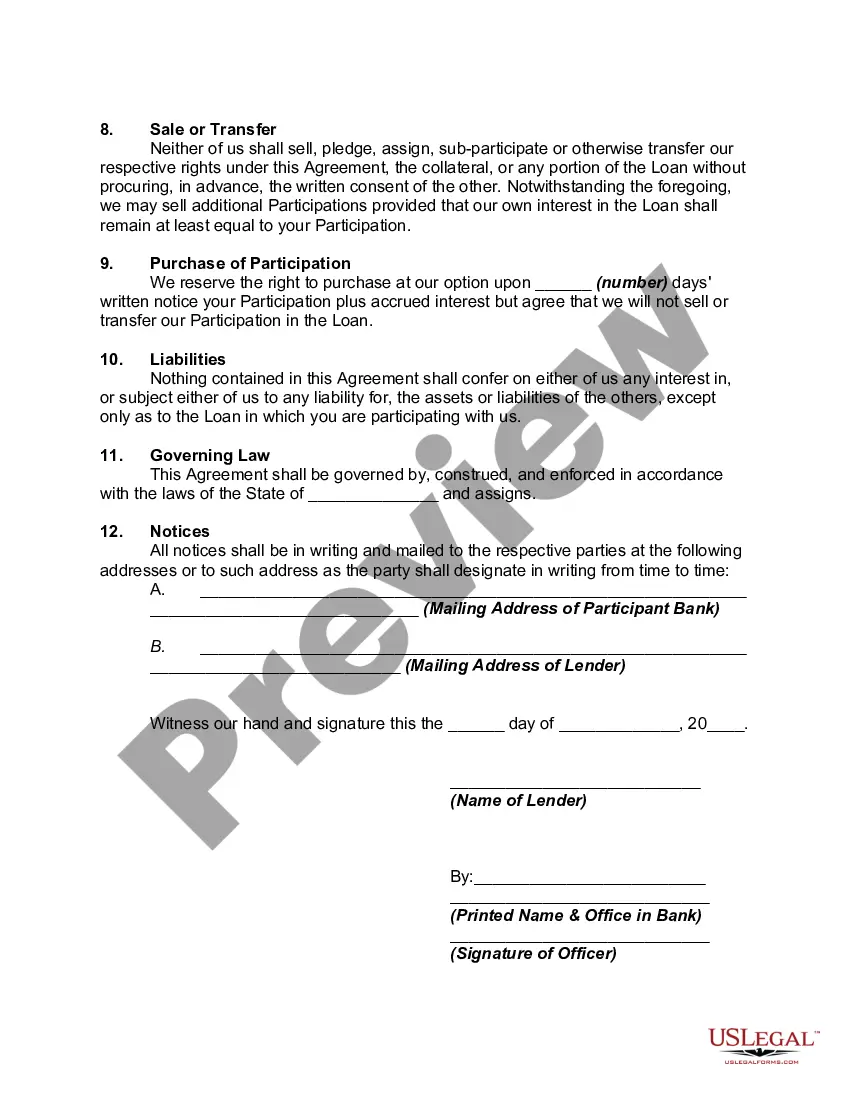
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
Lending agreements are governed by the Civil Code of the Philippines, along with other relevant laws such as the Lending Company Regulation Act and the Usury Law, although the latter is largely outdated due to the Central Bank's removal of interest rate ceilings.
A contract, under Philippine law, becomes binding as soon as there is mutual consent between the parties, consideration (payment or exchange of services), and a lawful object (subject matter of the agreement). These elements are enough to form a valid and enforceable contract, even without notarization.
While not required by law, having the promissory note notarized can provide additional legal protection and evidentiary weight in court should any dispute arise over its enforcement.
For example, companies X and Y enter a construction contract with X as the client and Y as the builder. Y then enters a collateral contract with Z, a materials supplier. If the materials are found defective, X may be able to sue Z even though they do not have a contract with one another.
Examples of collateral documents are a security agreement, guarantee and collateral agreement, pledge agreement, deposit account control agreement, securities account control agreement, mortgage, and UCC-1s.
A collateral assignment involves granting a security interest in the asset or property to a lender. It is a lawful arrangement where the borrower promises an asset or property to the lender to guarantee the debt repayment or meet a financial obligation.
Collateral documents include any documents granting a security interest in collateral by the borrower, parent or subsidiary in favor of the lender and all other documents required to be executed or delivered pursuant to those documents. Collateral documents do not include guaranties.
For example, when contracting a mortgage, the bank asks the customer to provide their house as collateral. If the customer fails to meet the repayment terms of their mortgage, the bank has the right to take ownership of the house.
A collateral assignment involves granting a security interest in the asset or property to a lender. It is a lawful arrangement where the borrower promises an asset or property to the lender to guarantee the debt repayment or meet a financial obligation.
Collateral is when an asset is pledged to secure repayment. The five main types of collateral are consumer goods, equipment, farm products, inventory, and property on paper. All can be used as collateral when applying for loans, provided there is a recognizable value associated with the item.