Examples Of Entertainment Packages In Pennsylvania
Description
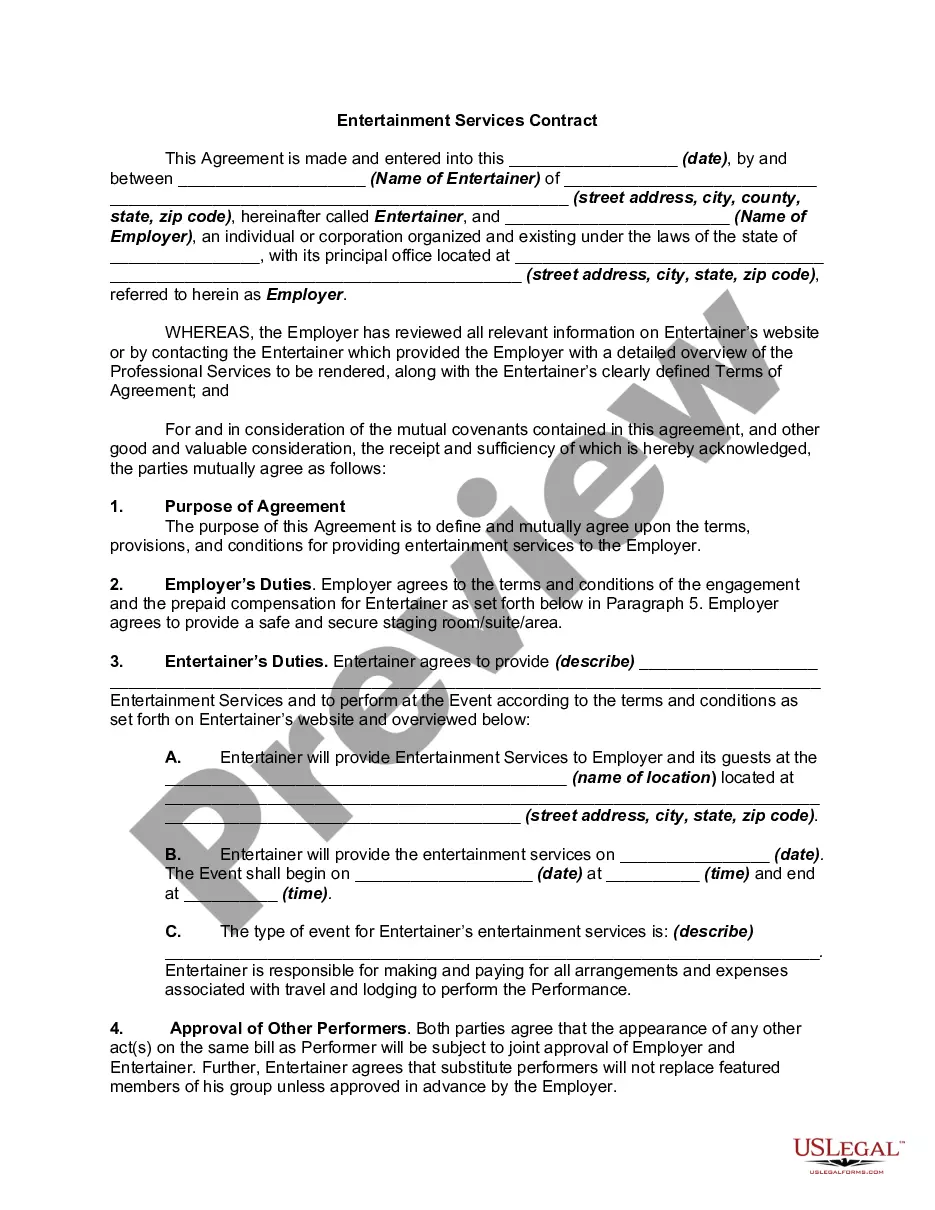
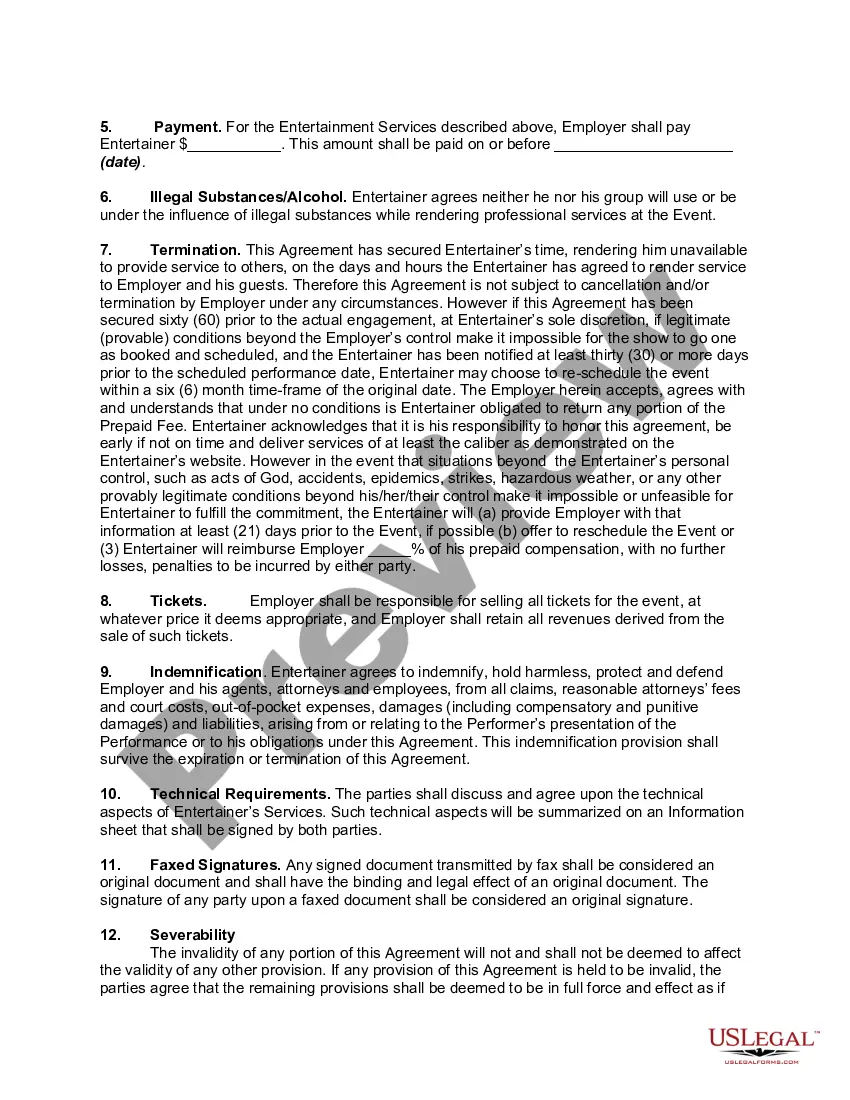
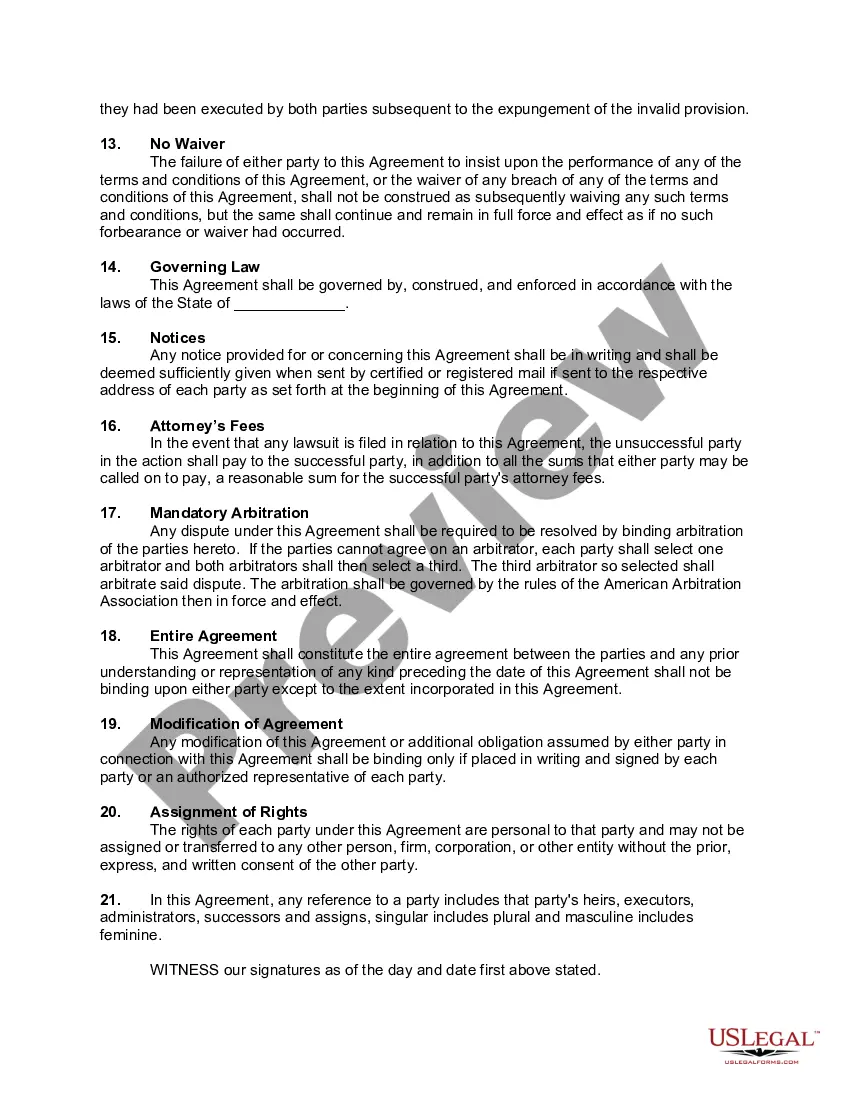
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
The employer requires employees to submit paper expense reports and receipts for: 1) any expense over $75 where the nature of the expense is not clear on the face of the electronic receipt; 2) all lodging invoices for which the credit card company does not provide the merchant's electronic itemization of each expense; ...
For travel or entertainment expenses to be deductible, documentation such as account books, logs, receipts, statements of witnesses, etc., must exist. The documentation must substantiate the amount, the time and place, the business purpose, and the business relationship with the person entertained.
The deduction for unreimbursed non-entertainment-related business meals is generally subject to a 50% limitation. You generally can't deduct meal expenses unless you (or your employee) are present at the furnishing of the food or beverages and such expense is not lavish or extravagant under the circumstances.
Pennsylvania allows 100 percent of customary and reasonable amounts expensed on business meals and entertainment. Sales tax on acquired property may be expensed currently rather than added to the basis of the property as required by the IRS.
Some examples include entertaining guests: at nightclubs; at social, athletic, and sporting clubs; at theaters; at sporting events; or. on hunting, fishing, vacation and similar types of trips.
Business Meals and Entertainment Expenses Pennsylvania allows 100 percent of customary and reasonable amounts expensed on business meals and entertainment.
