Life Insurance For Estate Taxes
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
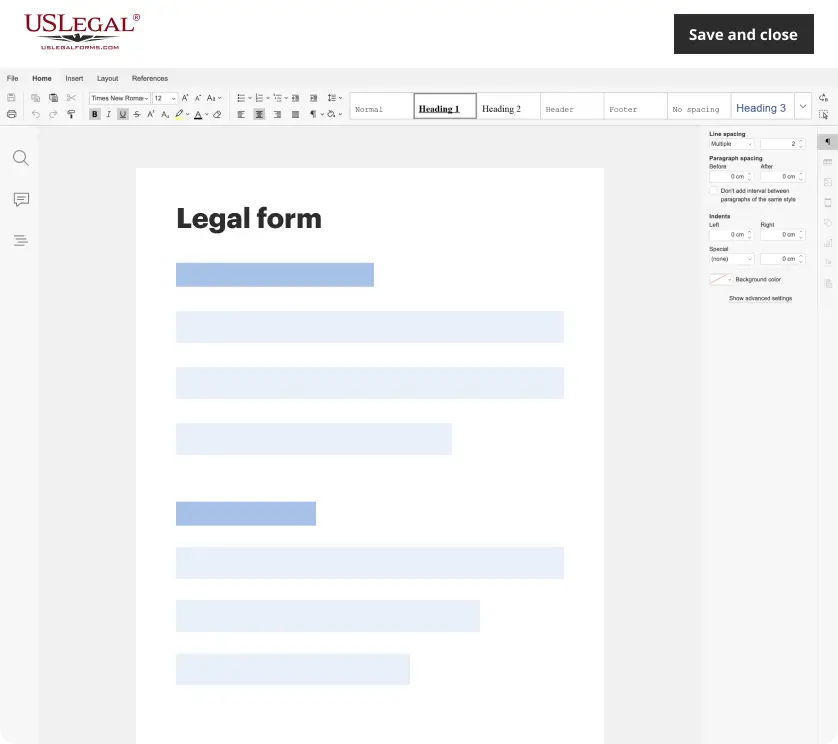
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
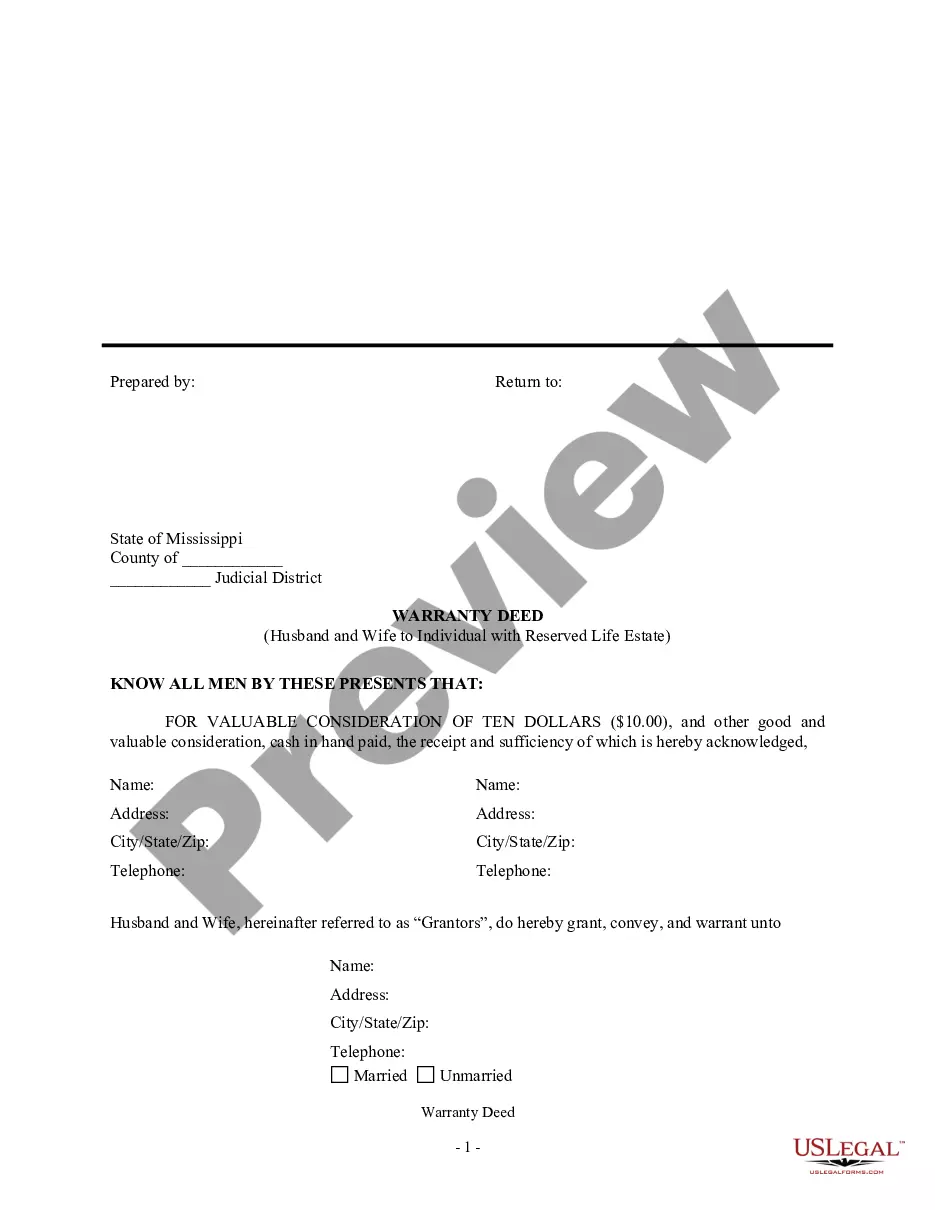
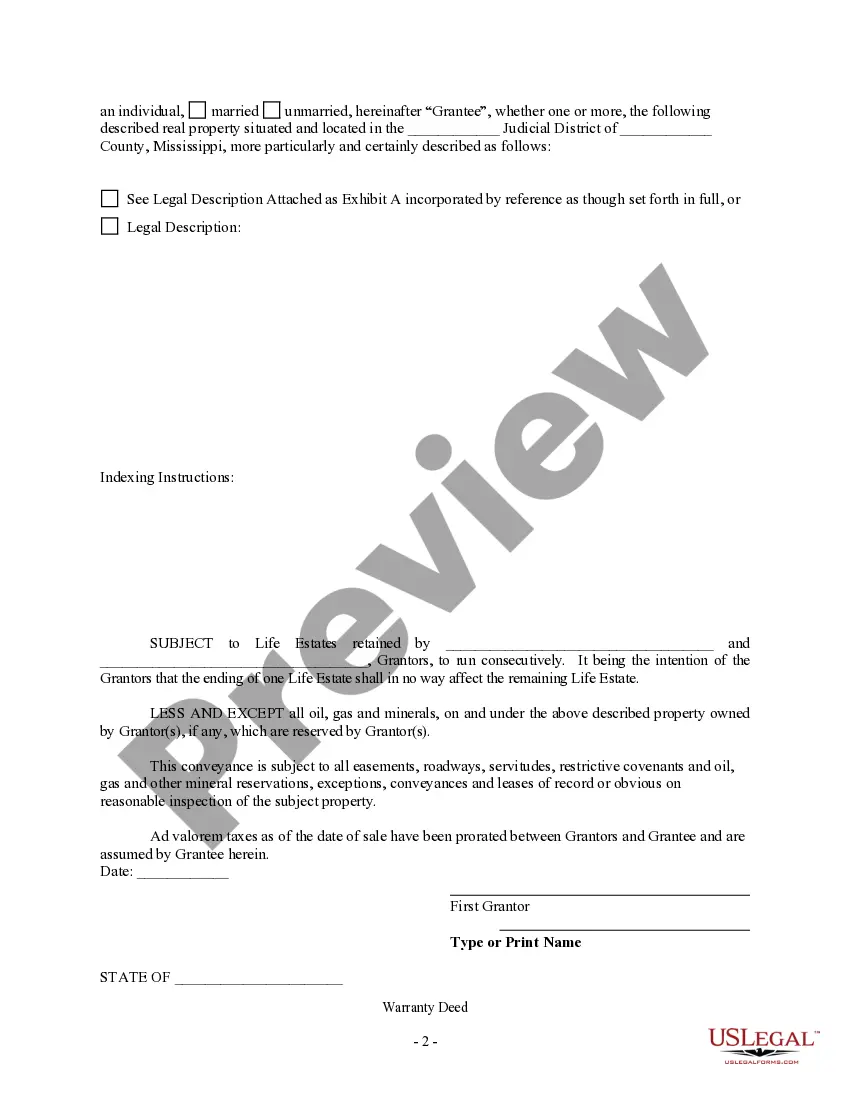
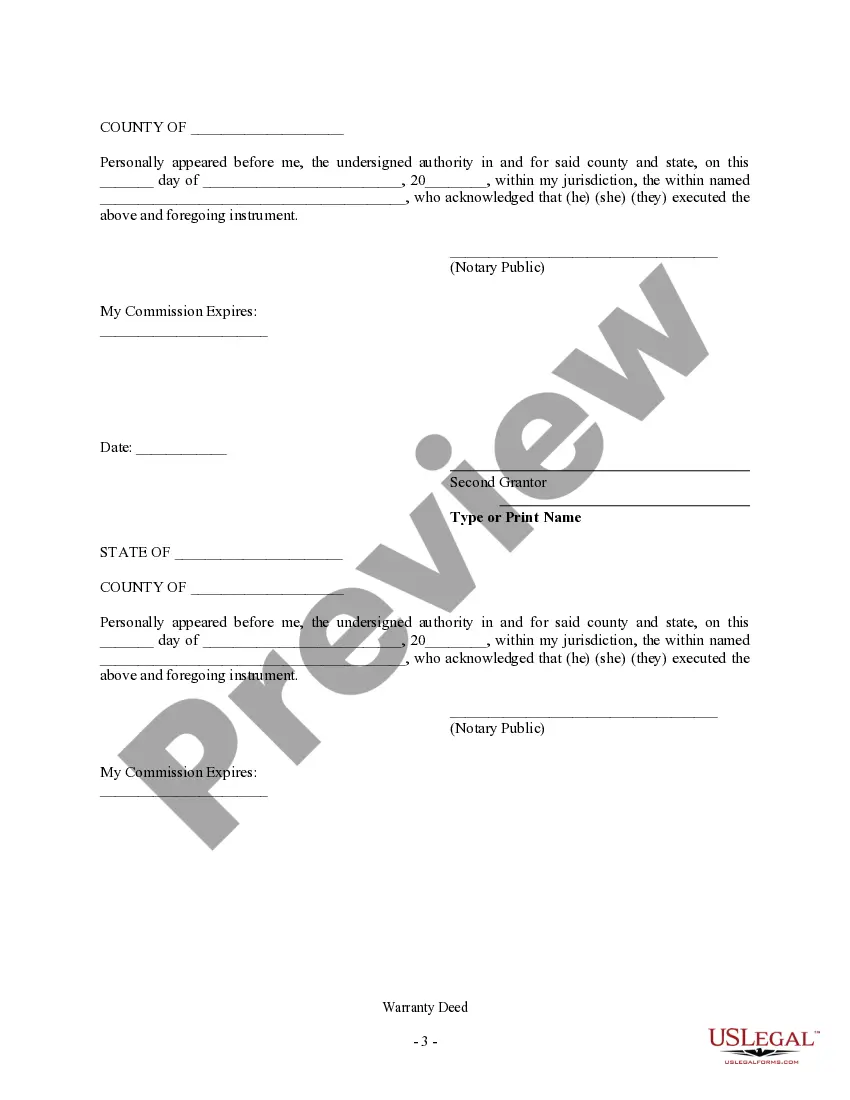
How to fill out Mississippi Warranty Deed To Child Reserving A Life Estate In The Parents?
- Log in to your US Legal Forms account if you're a returning user. Verify your subscription is active; if not, renew it promptly as per your payment plan.
- For first-time users, start by checking the Preview mode and description of the life insurance forms. Ensure you select the one that aligns with your local jurisdiction.
- If you find any discrepancies, use the Search tab to explore additional options until you locate the suitable template.
- Proceed to purchase the document by clicking the Buy Now button. Choose the subscription plan that fits your needs and register an account for access.
- Complete your transaction by entering your payment details, whether through credit card or PayPal.
- After your purchase, download the form to your device, and you'll have access to it under the My Forms section of your profile whenever needed.
By following these steps, you can easily secure the legal documents necessary for managing your estate and tackle potential tax liabilities with confidence.
Experience the ease of managing your estate planning today by visiting US Legal Forms and getting started!
Form popularity
FAQ
To avoid estate tax with life insurance, consider placing the policy in an irrevocable life insurance trust (ILIT). This strategy allows the life insurance proceeds to be excluded from your taxable estate, preserving more wealth for your beneficiaries. By effectively using life insurance for estate taxes, you can minimize your estate's tax burden and ensure a smoother transfer of assets.
When you receive life insurance proceeds, you typically do not need to report them as taxable income on your tax return. However, any interest earned on the proceeds while they are in the insurance company's hands may be taxable. For effective estate planning, you should consider how life insurance for estate taxes fits into your overall financial strategy, potentially keeping these funds outside of your taxable estate.
A life insurance policy may indeed be included in your gross estate, depending on policy ownership. If you retain any incidents of ownership during your lifetime, the policy’s value is usually counted toward your estate. This reality highlights the importance of understanding how life insurance for estate taxes works. Our platform at US Legal Forms can help you navigate these considerations effectively.
Generally, when a life insurance policy is owned by the deceased, it usually counts toward the overall value of the estate. However, if the policy naming a beneficiary directly, the benefit can pass outside the estate. Utilizing life insurance for estate taxes can be a strategic move to minimize financial burdens. It's beneficial to consult with a financial advisor to determine your specific situation.
Yes, life insurance can be considered part of an estate, depending on ownership and beneficiary designations. If the policyholder owns the life insurance, the proceeds may be included in the total estate value upon their death. Understanding how life insurance for estate taxes operates can help you plan for potential tax implications. Engaging with professionals can offer clarity on how this intersects with your estate planning.
Life insurance can effectively reduce estate taxes for many individuals. By strategically planning and possibly transferring ownership of the policy to an Irrevocable Life Insurance Trust (ILIT), the death benefit can remain outside your taxable estate. This strategy enhances your estate planning, positioning life insurance for estate taxes as a valuable asset.
Life insurance is typically viewed as part of your estate, especially if you hold the policy at the time of your death. The death benefit pays out to your named beneficiaries, but it may impact the overall value of your estate for tax purposes. Proper planning can help you manage these implications, making life insurance for estate taxes a wise choice.
Yes, a life insurance policy is generally considered part of your estate. However, the death benefit may not be included in taxable estate value, depending on the ownership structure of the policy. Understanding how life insurance for estate taxes works is essential in planning appropriately for your heirs.
Life insurance proceeds are generally not taxable and do not need to be reported as income. However, if the proceeds generate interest or other income, that must be reported on your tax return. If you have questions regarding the tax implications of life insurance for estate taxes, it's beneficial to consult experts on our platform for personalized advice.
When reporting life insurance on an estate tax return, you must include both the policy's value and the beneficiary's details. Ensure that any outstanding premiums are also noted. Proper reporting of life insurance for estate taxes is vital to avoid potential penalties. Consulting with legal professionals on our platform can help clarify these procedures.