S Corporation With Passive Income In Orange
Description
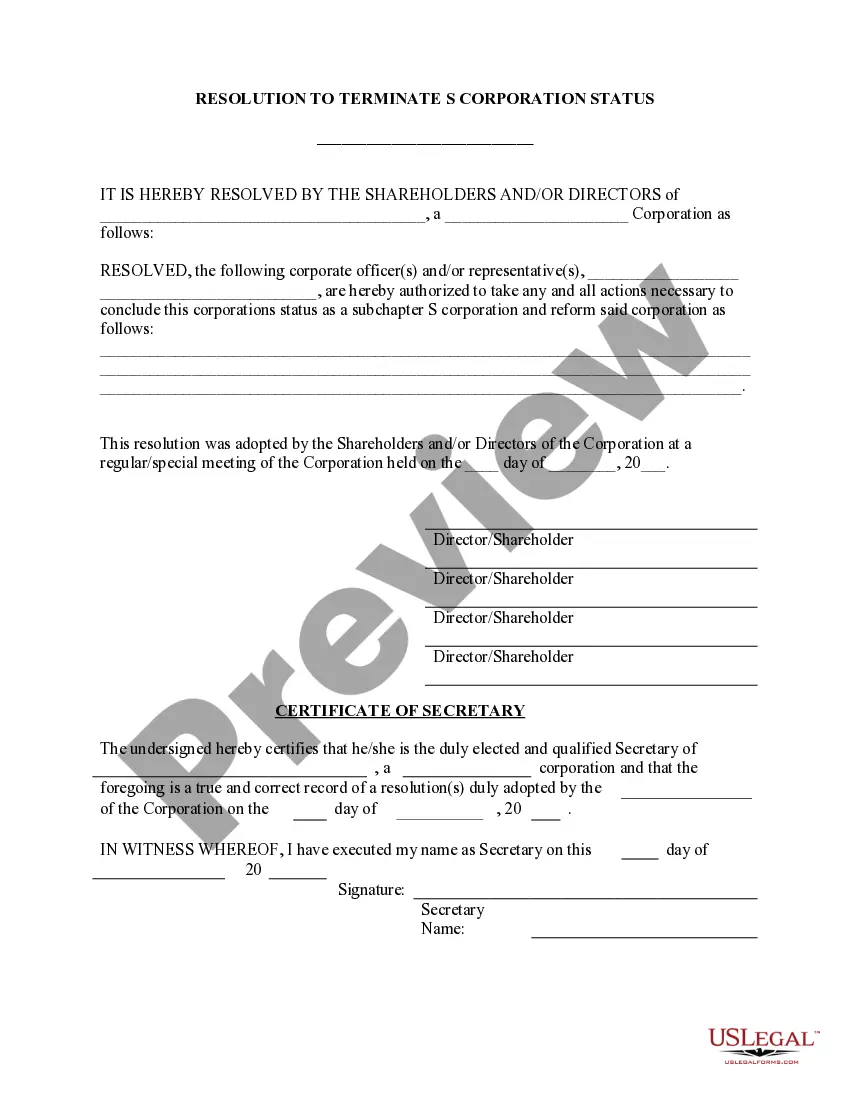
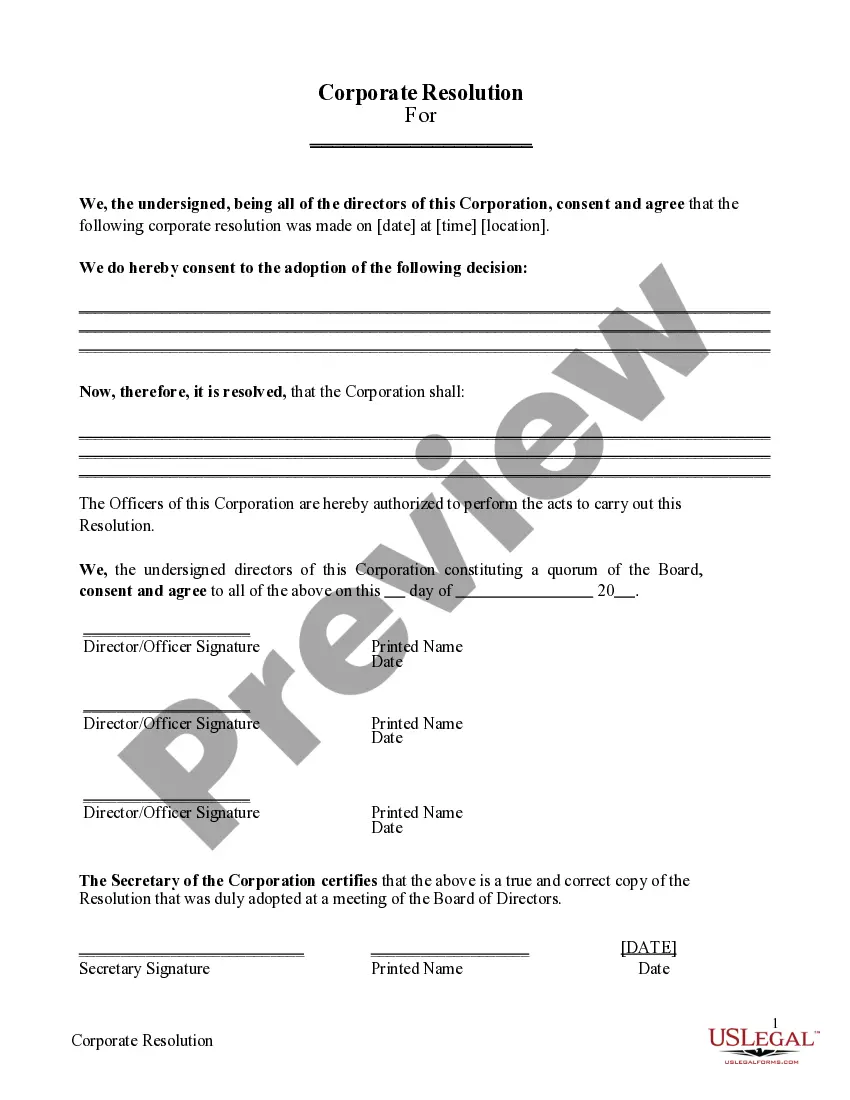
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
S corporations that were formerly C corporations are subject to a special tax if their passive investment income (such as dividends, interest, rents, royalties, and stock sale gains) exceeds 25% of their gross receipts, and the S corporation has accumulated earnings and profits carried over from its C corp years.
After conversion from a C corp, an S corporation can inherit income such as rent, interest, retained earnings, funds derived from stock sales, etc. Passive income that makes up more than 25% of an S corp's gross income is subject to tax.
If your previous entity was a C-Corp, you should close out its retained earnings before the conversion. The negative retained earnings balance will be transferred to a new equity account in the S-Corp.
Start with Schedule E, then use Form 8582, Passive Activity Loss Limitations, to summarize income and losses from passive activities, and to compute the deductible losses and any non-deductible losses to be carried forward to future years.
Passive income consists of amounts derived from royalties, rents, dividends, interest and annuities. Although conventional rental income is passive in nature, rents derived from an activity where the S corporation/lessor renders significant services or incurs substantial costs will not be treated as passive income.
More bad news- Normally, Net Operating Losses (NOLs) can be carried forward and used in future years for C Corps. On the other hand, unused NOLs will be lost forever with an S corporation election unless the C Corp can use it for previous years through amended tax returns.
Start with Schedule E, then use Form 8582, Passive Activity Loss Limitations, to summarize income and losses from passive activities, and to compute the deductible losses and any non-deductible losses to be carried forward to future years.
Start with Schedule E, then use Form 8582, Passive Activity Loss Limitations, to summarize income and losses from passive activities, and to compute the deductible losses and any non-deductible losses to be carried forward to future years.
Because of the one-class-of-stock restriction, an S corporation cannot allocate losses or income to specific shareholders. Allocation of income and loss is governed by stock ownership, unlike partnerships or LLCs taxed as partnerships where the allocation can be set in the partnership agreement or operating agreement.