
Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the Commercial Loan Review Template online
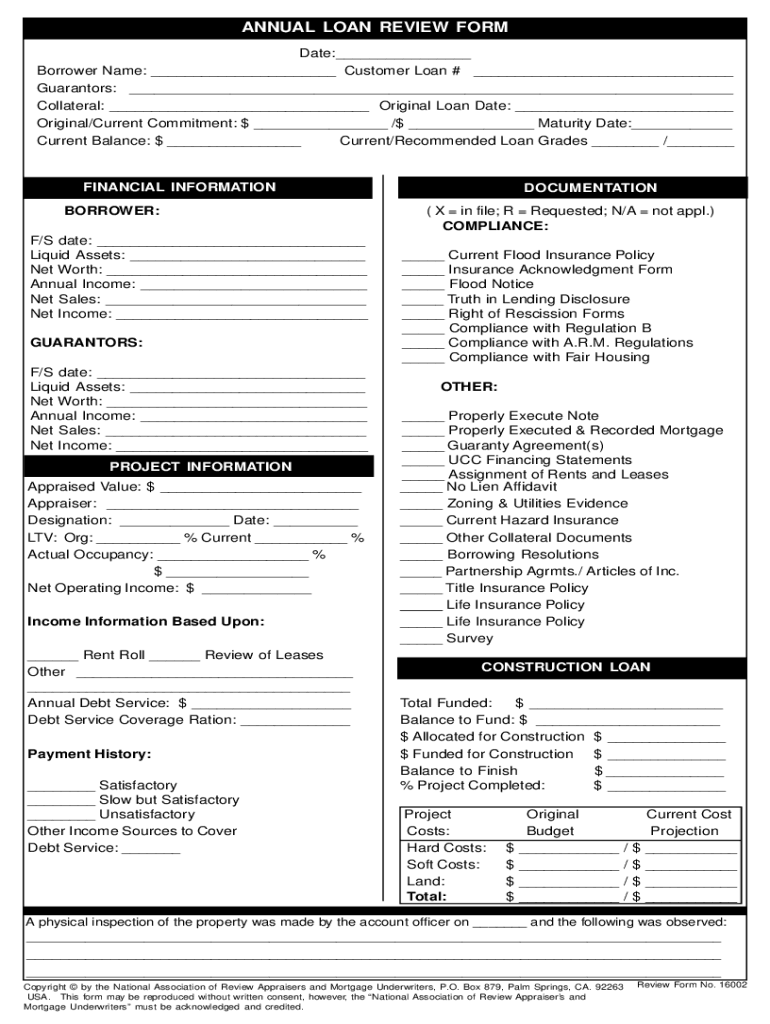
This guide provides clear and detailed instructions on how to effectively complete the Commercial Loan Review Template online. By following these steps, you can ensure that all necessary information is accurately entered for a comprehensive review.
Follow the steps to successfully complete the Commercial Loan Review Template.
- Click ‘Get Form’ button to access the Commercial Loan Review Template and open it in your preferred editor.
- Begin by entering the date of the review. This helps in tracking the review process and provides context for the subsequent entries.
- Fill out the borrower information, including the borrower's name and customer loan number. This section is crucial for identifying the loan under review.
- Provide details regarding any guarantors. List their names, which is essential for understanding the relationships involved in the loan agreement.
- Input collateral information, including the description and appraised value, followed by the original loan date, original/current commitment amounts, maturity date, and current balance. This data gives a full picture of the loan specifics.
- Complete the financial information section for both the borrower and any guarantors. This includes financial statement dates, liquid assets, net worth, annual income, net sales, and net income. Accurate entries are key to assessing financial health.
- In the project information section, fill out the appraised value, appraiser's name, LTV, actual occupancy percentage, and net operating income. Document income information based on rent roll, lease reviews, or other sources as applicable.
- Document the annual debt service and debt service coverage ratio. These metrics are critical for understanding loan repayment capacity.
- Review the payment history options, selecting the appropriate option based on the borrower's payment performance.
- Compile documentation status, marking the compliance items as current, requested, or not applicable. This section helps in ensuring all necessary documents are available.
- Complete the construction loan section, specifying the total funded amount, balance to fund, allocations for construction, and the percentage of project completed. Accurate reporting is vital for project oversight.
- Finally, add any observations from a physical property inspection conducted by the account officer. These notes can provide valuable context for the review.
- Once all sections are filled, use the options to save your changes, download, print, or share the completed form as necessary.
Start filling out the Commercial Loan Review Template online today to ensure a comprehensive loan review process.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
by D Nails · 2010 · Cited by 2 — This Technical Assistance Memo explains what a loan...
A commercial loan documentation guide is a comprehensive resource that outlines the...
by P Mathew · 2016 · Cited by 3 — The commercial mortgage loan process involves high...
Get answers to your most pressing questions about US Legal Forms API.
What are the three C's of commercial lending?
Students classify those characteristics based on the three C's of credit (capacity, character, and collateral), assess the riskiness of lending to that individual based on these characteristics, and then decide whether or not to approve or deny the loan request.
How are commercial loan rates determined?
Prime rates are established by the Federal Reserve, distinct from the U.S. treasury, through the federal funds target rate. Banks use the federal funds target rate to determine their loan rates. The prime rate is the federal funds target rate plus three.
What is a commercial loan review?
The commercial loan review involves obtaining and analyzing financial information, including other factors considered for the comprehensive review process. A commercial loan is a short-term loan given to business organizations by a financial institution to fulfil monetary requirements.
What are the 4 C's of commercial lending?
Commercial lending also has a set of four Cs: cash flow, collateral, credit, and character. Business owners seeking bank financing can benefit from understanding each of these.
How are commercial loans evaluated?
When evaluating commercial real estate loans, lenders consider the loan's collateral, the creditworthiness of the entity (or principals/owners), including three to five years of financial statements and income tax returns, and financial ratios, such as the loan-to-value ratio and the debt-service coverage ratio.
How are business loans evaluated?
They'll consider household income, business revenue, cash flow, outstanding debt, unused credit lines, and the amount of money the owner has personally invested into the business. All these variables will help lenders calculate the ability for an owner to repay the loan.
What are the 5 C's of commercial lending?
Lenders score your loan application by these 5 Cs—Capacity, Capital, Collateral, Conditions and Character. Learn what they are so you can improve your eligibility when you present yourself to lenders.
How does a bank evaluate a business for a commercial loan?
Banks look at EBITDA and compare it to the loan payment. They want to know that the business is generating more cash flow (EBITDA) than the amount of the loan payments. Typical minimum hurdles: With real estate: EBITDA must equal 1.25 times debt service (loan payments)
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.