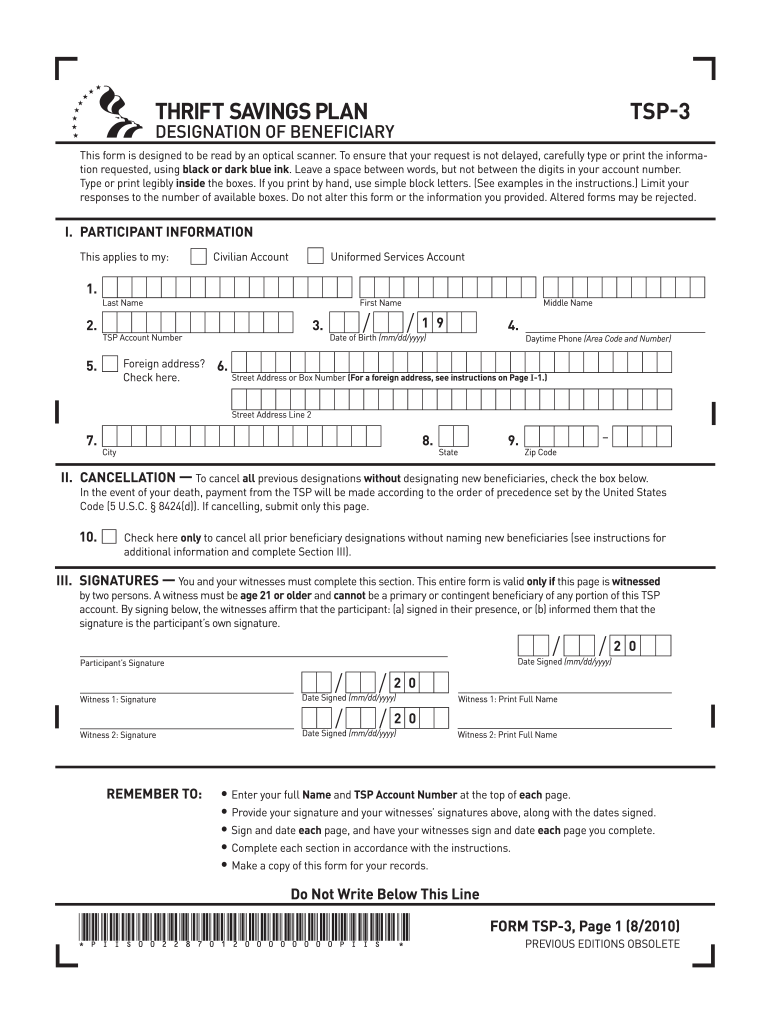
They have been combined into a single Form TSP-3. This version of Form TSP-3 should be used both by members of the uniformed services and by civilians. (Scroll down to view the form.) Thrift Savings Plan Form TSP-3 Designation of Beneficiary August 2010 For Federal civilian employees and members of the uniformed services Use this form to designate a beneficiary or beneficiaries to receive your Thrift Savings Plan (TSP) account after your death. If you would like your TSP account to be dis.

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the TSP-3 online
Filling out the TSP-3 form is an essential step in designating your beneficiaries for the Thrift Savings Plan. This guide will support you through each section of the form, ensuring your intentions are properly documented and clearly understood.
Follow these steps to successfully complete the TSP-3 form online.
- Click ‘Get Form’ button to obtain the form and open it in the editor.
- Complete the participant information section. Begin by choosing whether this applies to your civilian or uniformed services account. Provide your full name, date of birth, TSP account number, and contact information, ensuring legibility.
- If you want to cancel previous beneficiary designations without naming new ones, check the designated box in the cancellation section. If you are naming new beneficiaries, skip this step.
- In the primary beneficiaries section, invoke your beneficiaries' names, their relationship to you, and their respective shares of your TSP account. The total of the shares must equal 100 percent.
- If you have more than three primary beneficiaries, make additional copies of the primary beneficiary section, ensuring to include your name and TSP account number on each page.
- For contingent beneficiaries, designate who will receive your account should a primary beneficiary pass away. Similar naming conventions apply, and shares must also sum to 100 percent.
- Sign and date each page of the form, ensuring that two witnesses who meet the criteria also sign and date. Make sure your signature and the witnesses' signatures match on all pages.
- After completing the form, save your changes, and print a copy for your records. Then, mail the original document to the designated P.O. Box or fax it to the provided number.
Don't wait—complete your TSP-3 form online today to ensure your beneficiaries are designated according to your wishes.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
Use this form to designate a beneficiary or beneficiaries to receive your Thrift Savings...
by M Xiao · 2012 · Cited by 38 — The paper presents an O^*(1.2312^n)-time and...
You or others around you can be seriously injured or even killed if you don't use this...
Get answers to your most pressing questions about US Legal Forms API.
What is a TSP-3 form?
The TSP-3 form is the designation of beneficiary form related to your Thrift Savings Plan. This document allows you to choose who will receive your TSP benefits after your passing. It's essential to regularly review and update the TSP-3 form to reflect your current intentions and ensure your loved ones are taken care of.
Does TSP automatically go to spouse upon death?
TSP does not automatically transfer to a spouse without proper beneficiary designations. If you wish for your TSP to go to your spouse upon your death, ensure that they are listed on your TSP-3 form. Lack of designation can lead to complications and delays in accessing funds.
Who are the default beneficiaries for TSP?
If no beneficiaries are designated on your TSP-3 form, default beneficiaries apply as per TSP regulations. Typically, the distribution follows this order: spouse, children, parents, then other relatives. Because your specific situation may vary, consider updating your TSP-3 to ensure your intended beneficiaries receive your benefits.
How do I report my TSP on my taxes?
Reporting your TSP on taxes involves carefully tracking contributions and distributions. When you withdraw funds, that amount must be included as income on your tax return. Utilizing documents provided by your TSP account will make reporting clearer, ensuring compliance and accuracy in your TSP-3 reporting.
Does a spouse automatically inherit TSP?
Generally, a spouse does not automatically inherit TSP benefits unless designated as a beneficiary on your TSP-3 form. It is important to take proactive steps in estate planning to ensure your spouse is listed if that is your intention. If the TSP-3 is not completed, TSP benefits may go to different default beneficiaries as outlined by federal regulations.
Is my spouse entitled to my TSP?
Your spouse may have rights to your TSP depending on your marital status and whether there is a court order, like a divorce decree. Under federal law, a spouse is often entitled to a portion of TSP benefits acquired during the marriage. It's crucial to consult legal advice to understand the specifics of your situation regarding TSP-3 allocations.
How often can you take a TSP hardship withdrawal?
You can take a hardship withdrawal from your TSP-3 account only once in a 12-month period. This type of withdrawal is meant to help you cover immediate and pressing financial needs. Be sure to understand the rules and requirements for hardship withdrawals to make informed decisions about your TSP-3 funds.
What is a TSP 3 form?
The TSP-3 form is the official document used to designate beneficiaries for your Thrift Savings Plan account. By filling out the TSP-3 form, you can specify who will receive your funds upon your death. It is vital to keep this document updated to reflect any changes in your life circumstances.
What are the new rules for TSP beneficiaries?
Recently, the TSP has updated its rules regarding beneficiaries, making it essential to review your TSP-3 designations. New guidelines may influence how beneficiaries can access funds or what documentation is needed upon your passing. Stay informed about these changes to properly manage your TSP-3 account.
What is the 4% rule for TSP?
The 4% rule for TSP refers to the strategy that recommends withdrawing 4 percent of your retirement savings each year. This approach helps you maintain a steady income stream while minimizing the risk of exhausting your funds during retirement. If you're planning for retirement, understanding how the TSP-3 integrates with this rule is crucial for sustainable financial management. Seeking guidance from a financial expert can help you tailor this strategy to your needs.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.
This form is available in several versions. Select the version you need from the drop-down list below.