Counseling Notice: MI Generic (REV090913AP) 2.
Loading

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the Consumer Caution And Homeownership Counseling Notice online
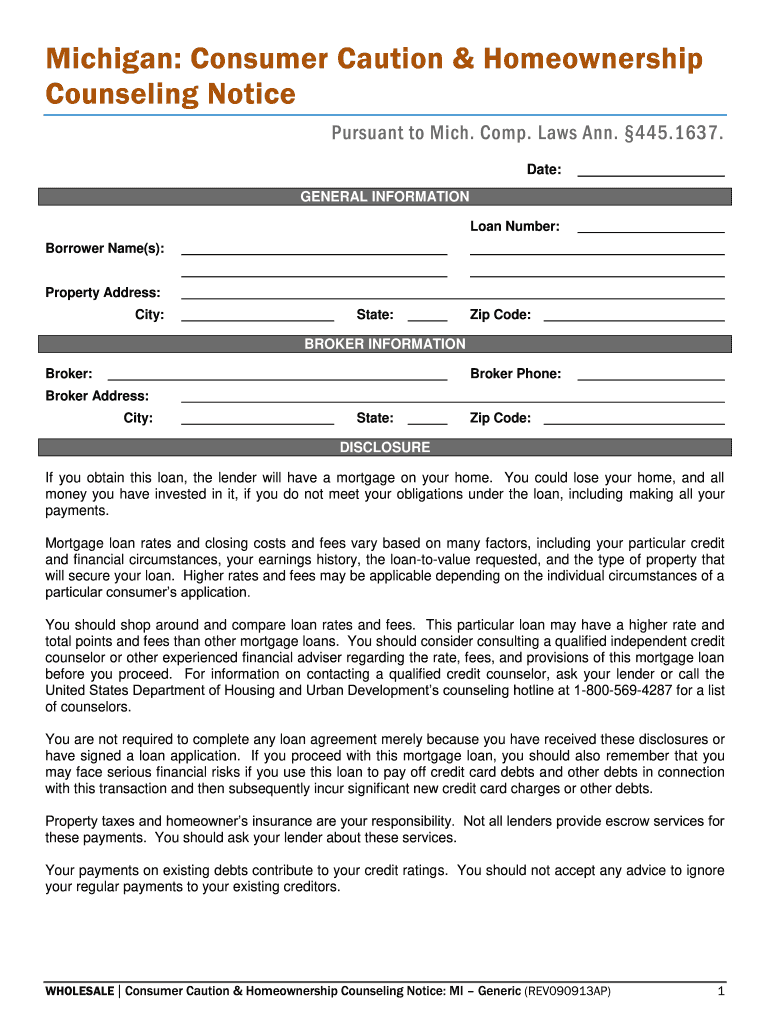
The Consumer Caution And Homeownership Counseling Notice is an essential document for borrowers seeking a mortgage loan. This guide provides step-by-step instructions on how to fill out the form online, ensuring that users understand each component thoroughly.
Follow the steps to successfully complete the form.
- Click ‘Get Form’ button to access the Consumer Caution And Homeownership Counseling Notice online.
- Enter the date of the document at the top of the form to ensure it is correctly dated.
- Fill in the loan number as provided by the lender, ensuring accuracy to avoid complications in processing.
- Provide the borrower name(s) in the designated fields, ensuring the names match official identification.
- Input the property address, including house number, street name, and any applicable unit or apartment numbers.
- Complete the fields for city, state, and zip code corresponding to the property address.
- In the broker information section, enter the broker's name and their contact number.
- Fill in the broker's address, including city, state, and zip code to complete this section.
- Review the disclosure section carefully, ensuring you are aware of the obligations and potential risks associated with the loan.
- Proceed to the acknowledgment section, where the loan originator and borrower(s) will need to sign and date the form.
- After completing all sections, review the form for accuracy and completeness before submitting it online.
- Once finalized, save changes, download the document, print it for your records, or share it as needed.
Complete the Consumer Caution And Homeownership Counseling Notice online today to ensure your homeownership journey starts on the right foot.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
The following are prohibited acts and limitations for covered loans: (a) (1) A covered...
without explicit permission provided that full credit, including © notice, is given to...
Jan 29, 2014 · To publish policy and procedures for Consumer-Level Supply per references...
Get answers to your most pressing questions about US Legal Forms API.
What is 106 C )( 5 of the Housing and Urban Development Act of 1968?
Section 106(c)(5) of the Housing and Urban Development Act of 1968 (12 USC 1701x(c)(5)) provides for homeownership counseling notifica tion by creditors to eligible homeowners.
When must a loan estimate be provided?
A Loan Estimate is a three-page form that you receive after applying for a mortgage. The Loan Estimate tells you important details about the loan you have requested. The lender must provide you a Loan Estimate within three business days of receiving your application.
What is the Dodd Frank Act requirement 1024.20 A )( 1?
Section 1024.20(a)(1) requires lenders to provide a written list of homeownership counseling organizations. Consistent with § 1024.20(a)(1), lenders comply with this requirement when they provide a list of ten HUD-approved housing counseling agencies.
What can a lender require before providing a loan estimate?
Loan officers are required to provide you with a Loan Estimate once you have provided: your name, your income, your Social Security number (so the lender can pull a credit report), the property address, an estimate of the value of the property, and. the desired loan amount.
What is Section 5 of respa?
(5) Assumption without lender approval. Any assumption in which the lender's permission is both required and obtained is covered by RESPA and this part, whether or not the lender charges a fee for the assumption.
What happens if a loan estimate is not sent within the 3 days?
If you did not get a Loan Estimate within three business days of submitting an application for a mortgage loan, contact your lender and ask if the Loan Estimate has been sent and when it was sent. The lender is required to send you a Loan Estimate within three business days of receiving your application.
When must a creditor provide a loan estimate before consummation?
Generally, a creditor is responsible for ensuring that a Loan Estimate is delivered to a consumer or placed in the mail to the consumer no later than the third business day after receipt of the consumer's “application” for a mortgage loan subject to the TRID Rule.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.