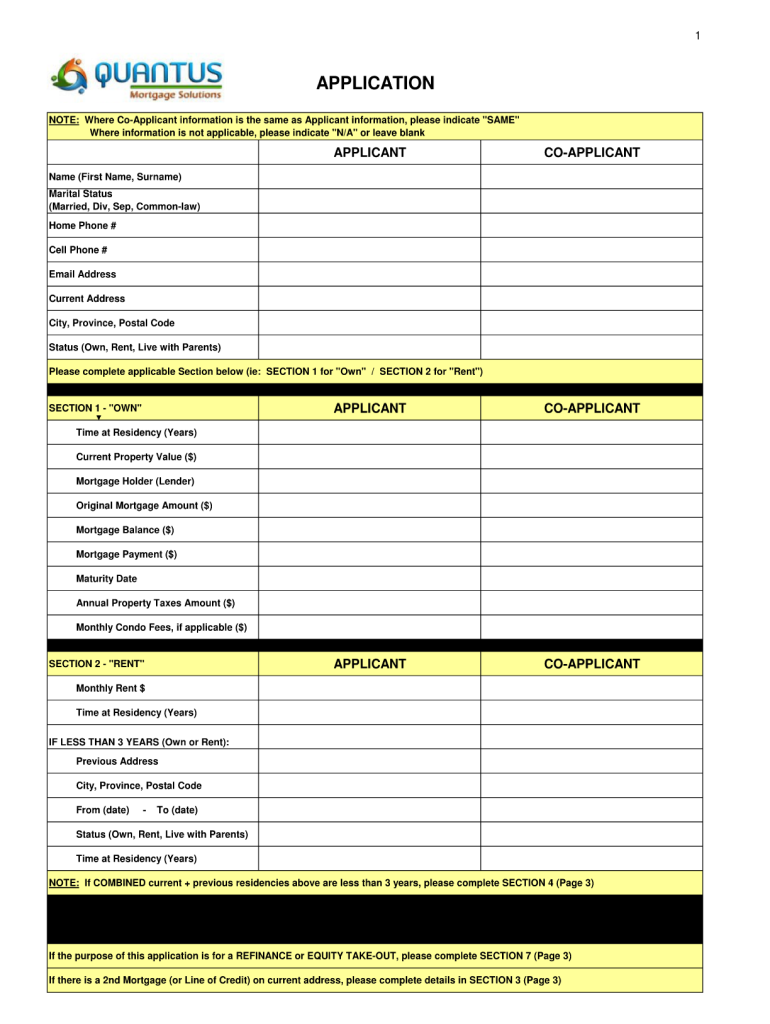

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the Qms Loans online
Filling out the Qms Loans form online can be a straightforward process when guided correctly. This comprehensive guide will provide step-by-step instructions to help you navigate each section efficiently.
Follow the steps to complete the Qms Loans form with ease.
- Press the ‘Get Form’ button to access the Qms Loans form and open it in the available editing interface.
- Begin with the personal information section. Enter your full name, address, and contact details accurately. Ensure that your information matches official documents to avoid any discrepancies.
- Proceed to the loan details section. Here, indicate the loan amount you are requesting, the purpose of the loan, and your preferred repayment period. Be specific and realistic in your estimations to expedite processing.
- Next, provide your financial information. This may include your employment status, monthly income, and any outstanding debts. Be honest and precise, as this information will be crucial in determining your eligibility.
- Review all entries for accuracy. Ensure that all fields are completed and that the information is consistent. It is advisable to double-check for typographical errors or omitted information.
- Once all sections are completed, save your changes. You will typically have options to download the form, print it for physical records, or share it as required.
Take the next step today by completing your Qms Loans form online!
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
Mar 27, 2023 — One category of qualified mortgages (QMs) is loans that are eligible for...
Feb 10, 2014 — The purpose of the QM rule is to help assure that borrowers have...
Mar 8, 2024 — The purpose of a data quality rule is to prevent, monitor or report...
Get answers to your most pressing questions about US Legal Forms API.
What loans are not subject to QM?
Several types of loans are not subject to QMs Loans, including open-end credit plans like home equity lines of credit, loans made by non-profit organizations that meet specific criteria, and certain temporary financing options. Additionally, loans that exceed the debt-to-income ratio limits may not qualify. Understanding the boundaries of QM can empower you in your borrowing journey. If navigating this complex terrain feels overwhelming, consider utilizing US Legal Forms for streamlined assistance and documentation.
What are the four types of a QM?
The four types of QMs Loans are: 1) General Qualified Mortgages, which comply with strict regulatory standards; 2) Temporary Qualified Mortgages, which cater to unique economic conditions; 3) Small Creditor Qualified Mortgages, created for local banks and credit unions; and 4) High-priced Qualified Mortgages, aimed at securing loans with elevated costs. By familiarizing yourself with these categories, you can navigate the mortgage landscape with confidence. If you have further questions, US Legal Forms can provide the necessary documentation and guidance.
What are the 4 types of qualified mortgages?
The four types of qualified mortgages, or QMs Loans, include: 1) General QMs, which meet specific criteria set by the Consumer Financial Protection Bureau; 2) Temporary QMs, designed for loans made during the COVID-19 pandemic; 3) Small Creditor QMs, intended for small lenders that often serve their local communities; and 4) High-priced QMs, which apply to loans with high closing costs. Each type prioritizes borrower protection and responsible lending. Understanding these categories can help you make informed decisions about your mortgage options.
What is the new QM rule?
The new QM rule brings updates to the previous regulations aimed at enhancing borrower protection. It introduces flexible features, such as varying debt-to-income limits, allowing for broader access to loans. As you explore Qms Loans, being aware of these changes can help you navigate your options more effectively. This adaptability can support your journey towards homeownership.
What is the DTI threshold for QM?
The Debt-to-Income (DTI) ratio threshold for Qualified Mortgages is generally set at 43%. This means that your total debt payments should not exceed 43% of your gross income. When investigating Qms Loans, keeping this ratio in mind is crucial. It helps assess your borrowing capacity and ensures you can comfortably manage repayments.
Does QM points and fees apply to VA loans?
Yes, QM points and fees apply to VA loans as well. This means that any fees charged should comply with the 3% cap set by QM regulations. If you are considering Qms Loans that are backed by the VA, awareness of this rule is essential. It ensures that your financial commitments remain reasonable and manageable.
What is the 3% rule for QM?
The 3% rule for Qms Loans refers to the cap on points and fees for certain types of loans, limiting them to 3% for loans over $200,000. This rule aims to make borrowing more accessible while protecting consumers from high costs. By staying informed about the 3% rule, borrowers can make smarter financial choices related to Qms Loans. For those who need assistance navigating these regulations, uslegalforms provides valuable tools and documents to streamline the process.
What types of loans are QM?
Any loan that meets the product feature requirements and is eligible for purchase, guarantee, or insurance by a GSE, FHA, VA, or USDA is QM regardless of the debt-to-income ratio (this QM category applies for GSE loans as long as the GSEs are in FHFA conservatorship and for federal agency loans until an agency issues ...
What are the new QM rules?
The General QM Final Rule requires the creditor to consider the consumer's DTI ratio or residual income and to consider and verify the consumer's income or assets other than the value of the dwelling and the consumer's debts.
What is the safe harbor rule for QM?
Under qualified mortgage rules, “safe harbor” provisions protect lenders against lawsuits by distressed borrowers who claim they were extended a mortgage the lender had no reason to believe they could repay.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.