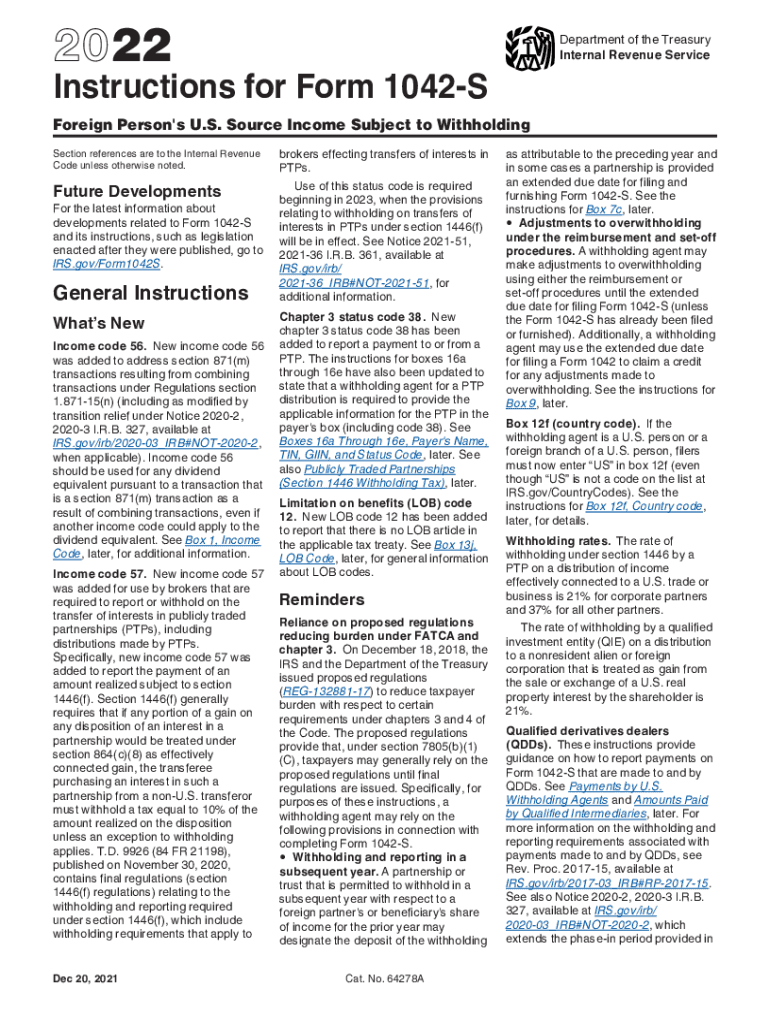
2022Department of the Treasury Internal Revenue ServiceInstructions for Form 1042S Foreign Person's U.S. Source Income Subject to Withholding Section references are to the Internal Revenue Code unless.
Loading

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the IRS Instruction 1042-S online
Filling out the IRS Instruction 1042-S online can seem daunting, but this supportive guide will walk you through each step with clarity. This form is used to report income paid to foreign persons subject to withholding.
Follow the steps to complete the form accurately.
- Press the ‘Get Form’ button to access and open the IRS Instruction 1042-S form in your online editor.
- Enter your unique form identifier at the top of the form.
- In box 1, input the appropriate income code from the list provided in the IRS instructions.
- In box 2, enter the gross amount of income you are reporting, ensuring it is in whole dollars.
- In box 3, indicate the chapter indicator by entering '3' for chapter 3 or '4' for chapter 4, depending on the nature of the payment.
- If applicable, complete boxes 3a and 4a with the appropriate exemption codes.
- Report the applicable tax rate in boxes 3b and 4b as required.
- Provide detailed information for the recipient, including name, country code in box 13, and address in boxes 13c and 13d.
- Complete any other relevant fields, ensuring all information matches the requirements specified in the instructions.
- Once you have filled out all necessary fields and double-checked for accuracy, you can save your changes, download, print, or share the completed form.
Get started by filling out your IRS Instruction 1042-S online today!
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
Use Form 1042-S to report: Income and amounts withheld as described in the Instructions...
Jan 24, 2018 - Foreign persons will receive form 1042-S if they receive any of the ... IRS...
Publication 4163 Modernized e-File (MeF) Information for Authorized IRS e-File ...... For...
Get answers to your most pressing questions about US Legal Forms API.
Do I have to issue a 1099 to a foreign person?
As long as the foreign contractor is not a U.S. person and the services are wholly performed outside the U.S., then no Form 1099 is required and no withholding is required. ... No Form 1099 then needs to be filed for payments to foreign persons. Treas.
Who must file Form 1042?
You file Form(s) 1042-S to report to a recipient tax withheld by your withholding agent. You pay gross investment income to foreign private foundations that are subject to tax under section 4948(a). You pay any foreign person specified federal procurement payments that are subject to withholding under section 5000C.
What is a 1042 form used for?
Form 1042-S is used to report amounts paid to foreign persons (including persons presumed to be foreign) that are subject to income tax withholding, even if no amount is deducted and withheld from the payment because of a treaty or exception to taxation, or if any amount withheld was repaid to the payee.
What is the difference between 1099 and 1042?
A 1099 form is used to report miscellaneous income, such as gross rent, for US residents and businesses only, whereas a 1042-S (Foreign Person's U.S. Source Income Subject to withholding) is used to report income paid to a non-resident regardless of whether the payment is taxable.
Can Form 1042 be filed electronically?
Any person, including a corporation, partnership, individual, estate, and trust, that is required to file 250 or more Forms 1042-S per year must file such returns electronically. ... If you are filing 250 or more Form 1042-S corrections, they must be filed electronically.
What does 1042 S mean?
Form 1042-S. A form that one files with the IRS to report certain U.S. income of a foreign person that is subject to withholding. It is especially used for income derived from a nominee or a publicly-traded partnership.
What is the difference between 1042 and 1042s?
The main difference between forms 1042 and 1042-S is that form 1042-S is concerned with payments made to foreign persons, while form 1042 is concerned with determining how much income will be withheld for tax withholding purposes.
What is Chapter 3 and Chapter 4 on 1042s?
Chapter 3 withholding applies only to payments made to a payee that is a foreign person. ... Chapter 4 withholding applies to withholdable payments made to an entity payee that is an FFI unless the withholding agent is able to treat the FFI as a participating FFI, deemed-compliant FFI, or exempt beneficial owner.
What is a 1042 s used for?
Form 1042-S is used to report amounts paid to foreign persons (including persons presumed to be foreign) that are subject to income tax withholding, even if no amount is deducted and withheld from the payment because of a treaty or exception to taxation, or if any amount withheld was repaid to the payee.
What is 1042 S reporting?
Form 1042-S is used to report amounts paid to foreign persons (including persons presumed to be foreign) that are subject to income tax withholding, even if no amount is deducted and withheld from the payment because of a treaty or exception to taxation, or if any amount withheld was repaid to the payee.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.