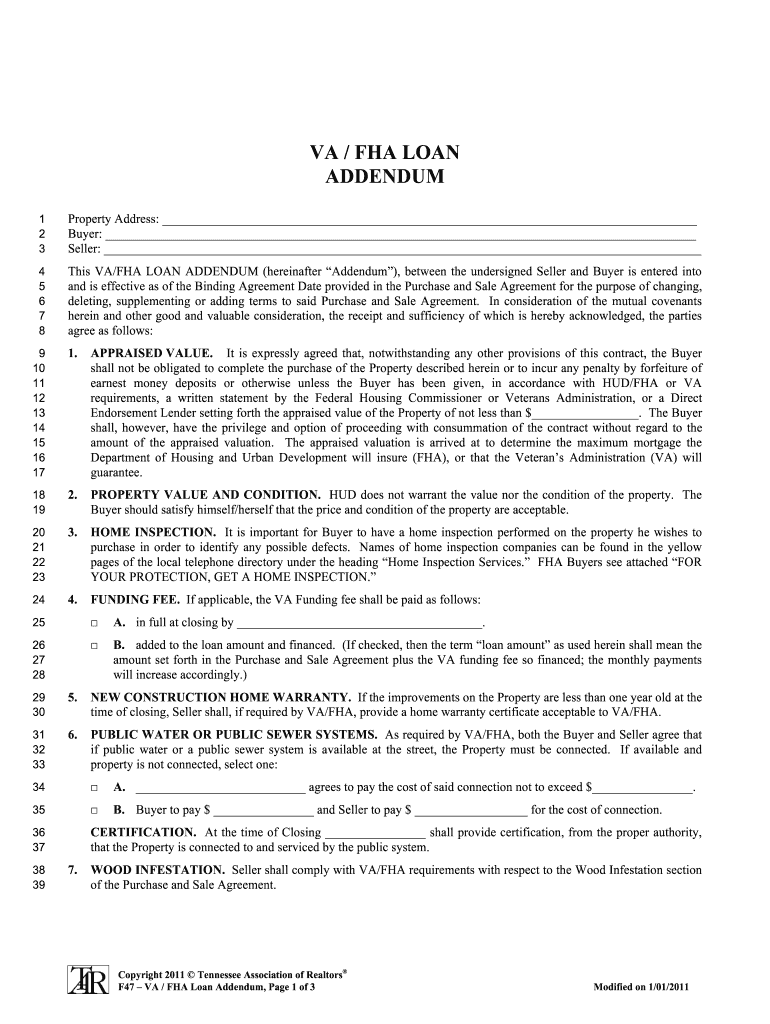
VA / FHA LOAN ADDENDUM 1 2 3 Property Address: Buyer: Seller: 4 5 6 7 8 This VA/FHA LOAN ADDENDUM (hereinafter Addendum ), between the undersigned Seller and Buyer is entered into and is effective.
Loading

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to use or fill out the VA / FHA LOAN ADDENDUM - Georgia Evans online
Filling out the VA / FHA Loan Addendum is an essential step in the home-buying process, particularly for those utilizing government-backed loans. This guide will help you navigate through each section of the form confidently, ensuring you complete it accurately and effectively.
Follow the steps to complete the form online:
- Click the ‘Get Form’ button to obtain the form and open it in your preferred editor.
- Begin by entering the property address in the designated field. Ensure that the address is complete and accurate to avoid any issues during the loan process.
- Next, fill in the names of the buyer and seller in the appropriate sections. Use the full names as they appear on legal documents.
- In section 1, specify the appraised value of the property as required by HUD/FHA or VA guidelines. This value is essential for determining the maximum loan amount.
- For section 2, be aware that HUD does not warrant the value or condition of the property. It is recommended that the buyer verify that the property meets their expectations.
- Section 3 emphasizes the importance of having a home inspection performed. It is advisable for the buyer to find a reputable home inspection service.
- In section 4, indicate how the VA funding fee will be handled. You can choose to pay it at closing or have it added to the loan amount.
- Section 5 addresses new construction home warranties. If the property is less than one year old, ensure the seller will provide the required warranty.
- In section 6, confirm the connection to public water or sewer systems. Select who will be responsible for the connection costs if applicable.
- For section 7, assure compliance with VA/FHA wood infestation requirements by checking the corresponding box.
- Section 8 outlines any non-allowable settlement charges that the seller agrees to pay. Fill in the appropriate amounts as necessary.
- Finally, ensure all signatures are collected in the certification section and that all parties receive a copy. You can then save changes, download, print, or share the form as needed.
Complete your documents online now for a smooth loan process.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
LHP Capital, LLC is going to acquire and rehab Meadow Lane Apartments by using an FHA...
Eligible Loans Warranties and Representations Loan Requirements Interest Rate Mortgage...
Get answers to your most pressing questions about US Legal Forms API.
What is a VA addendum?
A VA addendum is a vital document used in real estate transactions involving VA loans. This addendum provides essential details about the property and ensures compliance with VA loan requirements, protecting both buyers and sellers. If you are navigating the VA / FHA LOAN ADDENDUM - Georgia Evans, this document streamlines the buying process and clarifies important terms. Understanding the VA addendum can help you make informed decisions when securing your VA loan.
How hard is it to qualify for FHA?
Qualifying for an FHA loan can be straightforward, especially if you meet the basic requirements. Generally, applicants need a credit score of at least 580 for the best rates, but some lenders may work with scores as low as 500. Additionally, your income, employment history, and debt-to-income ratio play significant roles. Remember, utilizing a VA / FHA LOAN ADDENDUM - Georgia Evans can streamline the process and guide you through the necessary steps to achieve homeownership.
What is a VA financing addendum?
TO. REAL ESTATE PURCHASE CONTRACT. THIS IS AN ADDENDUM to that REAL ESTATE PURCHASE CONTRACT (the “REPC”) with an Offer Reference Date of , 20 , including all prior addenda and counteroffers, between as Buyer, and as Seller, regarding the Property located at .
What is a FHA addendum to purchase agreement?
The FHA amendatory clause gives you the right to back out of buying a home without losing any money if the value doesn't at least match the sales price. It's just one of many disclosures you'll sign if you take a loan backed by the Federal Housing Administration (FHA).
What is third party financing in mortgage?
A third-party origination is defined as any mortgage that is completely or partially originated, processed, underwritten, packaged, funded, or closed by an entity other than the lender who sells the mortgage to Fannie Mae, such as a mortgage broker or correspondent.
What does the date in the third party financing addendum provide a deadline to buyers for?
The date in the Third Party Financing Addendum provides a deadline to buyers for informing a seller they didn't get their financing approved. If the buyer fails to notify the seller within that termination time period that they did not receive buyer approval, the buyer forfeits their right to the earnest money.
What is the third party financing addendum on a VA loan?
A third (3rd) party financing addendum is attached to a sales contract that outlines the terms of a loan (e.g., conventional, FHA, VA) that is agreeable to the buyer in order to close on the property. The sales contract is usually contingent upon the buyer receiving the loan as detailed in the addendum.
What does the use of a third party financing addendum typically involves?
The use of a Third Party Financing Addendum typically involves: a buyer obtaining a loan from a mortgage lender. In the Loan Assumption Addendum, the Notice to Buyer states that: the buyer should examine the existing loan before assuming it.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.