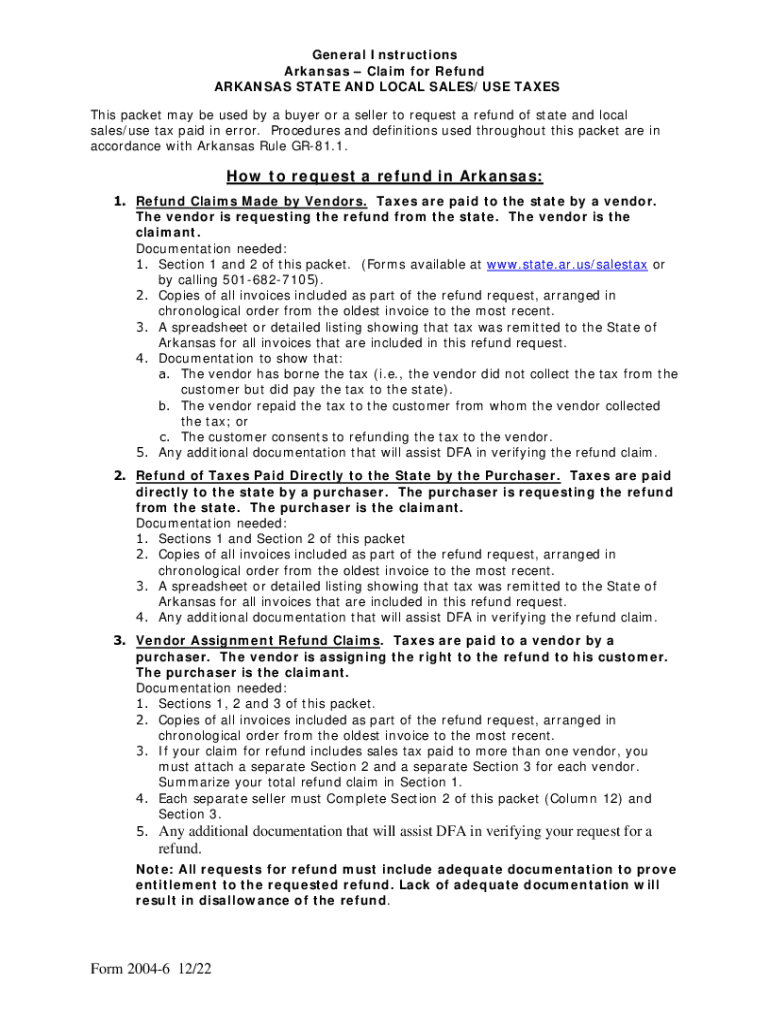
General Instructions Arkansas Claims for Refund ARKANSAS STATE AND LOCAL SALES/USE TAXES This packet may be used by a buyer or a seller to request a refund of state and local sales/use tax paid in.
Loading

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the AR 2004-6 online
The AR 2004-6 form is crucial for anyone seeking a refund of sales or use tax paid in error in Arkansas. This guide will provide you with detailed instructions on how to fill out this form online, ensuring you have all the necessary information and documentation ready.
Follow the steps to complete your online AR 2004-6 refund request efficiently.
- Press the ‘Get Form’ button to access the AR 2004-6 form and open it in the designated online tool.
- Fill out Section 1: Claim Information. Provide your name, Federal I.D. Number, address, social security number, and other contact details. Specify the period for which you are requesting the refund and the total amount you wish to claim.
- Attach the required documentation as outlined for your category (vendor, purchaser, or vendor assignment). This includes invoices, spreadsheets detailing the taxes remitted, and any additional supporting documentation.
- Complete Section 2, detailing each transaction. Enter the invoice date, vendor name, invoice number, and descriptions. Make sure to provide thorough explanations for any exemptions claimed and ensure all corresponding taxes are listed correctly.
- If you are a vendor assigning the refund, complete Section 3. Ensure the seller's details are filled in, including their sales/use tax permit number and signature.
- Review the entire form for completeness. Ensure that all required fields are filled and that you have included all necessary documentation to avoid rejection.
- Once you finalize the form, save your changes. You can then download, print, or share the document as needed.
Complete your AR 2004-6 refund request online today for a smooth and efficient process.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
This packet may be used by a buyer or a seller to request a refund of state and local...
(Also § 501.) Rev. Rul. 2004-6. Organizations that are exempt from federal income tax...
Fluid capacities and tire pressures. Owner's Identification Form. Page 2. Congratulations!...
Get answers to your most pressing questions about US Legal Forms API.
How far back can a state tax audit go?
How far back can a sales tax audit go. The California sales tax audit statute of limitations is 3 years for taxpayers who have filed tax returns. That means the BOE has three years within which they can audit those returns. However, if you fail to file tax returns, the statute of limitations is 8 years.
What is ark code ann 26 18 507?
Act 718 of 2021 amends Arkansas Code Annotated 26-18-507 to allow the Department of Finance to use a refund due to a taxpayer as payment of an outstanding state tax delinquency of the taxpayer after a final assessment has been issued for the delinquency.
What is the statute of limitations for sales tax refund in Arkansas?
The statute of limitations that applies to tax refunds is found at Ark. Code Ann. § 26-18-306. Refund claims are within the statute of limitations if they are filed within three years from the date the return was filed or two years from the date the tax was paid, whichever is later.
What is the limitations period for tax refunds?
Submitting a Claim for Refund Generally, you must file a claim for a credit or refund within three years from the date you filed your original tax return or two years from the date you paid the tax, whichever is later.
What is the statute of limitations for US sales tax?
If the taxpayer failed to file a return, the statute of limitations extends to 7 years from either the return due date or the return filing date, whichever comes later.
What is the statute of limitations on sales tax in Arkansas?
Arkansas Code 26-18-306 defines the statute of limitations for sales tax assessment as 3 years from either the return due date or the return filing date (whichever comes later). However, if the taxable sales are misreported by more than 25%, then the statute of limitations is increased to 6 years.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.