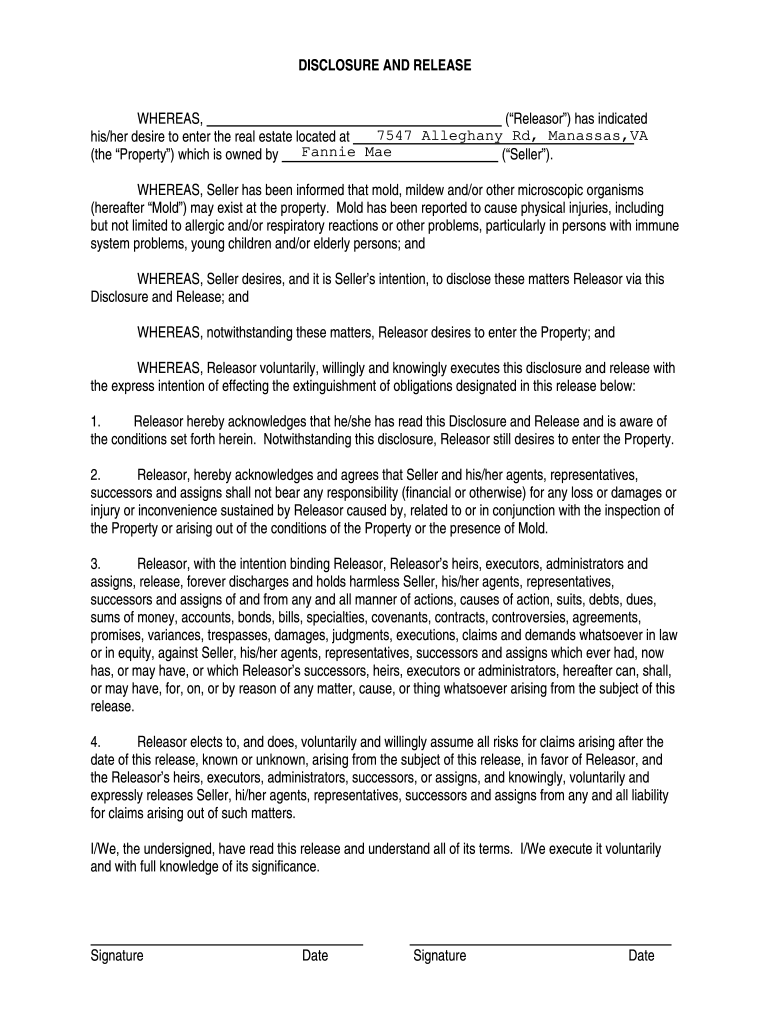
R”). WHEREAS, Seller has been informed that mold, mildew and/or other microscopic organisms (hereafter “Mold”) may exist at the property. Mold has been reported to cause physical injuries, including but not limited to allergic and/or respiratory reactions or other problems, particularly in persons with immune system problems, young children and/or elderly persons; and WHEREAS, Seller desires, and it is Seller’s intention, to disclose these matters Releasor via this Disclosure and Release.

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the Fannie Mae Disclosure and Release online
Filling out the Fannie Mae Disclosure and Release form online is a straightforward process that ensures you understand the conditions related to the property you wish to enter. This guide will walk you through each section of the form, providing you with clear instructions to ensure a smooth completion.
Follow the steps to complete the form online.
- Click ‘Get Form’ button to obtain the form and open it in your preferred editing tool.
- Begin by entering the name of the Releasor in the designated field, along with their property address (e.g., 7547 Alleghany Rd, Manassas, VA). This identifies the individual expressing their desire to enter the property.
- In the next section, acknowledge the existence of mold, mildew, and other microscopic organisms at the property. Confirm that you understand the potential physical injuries these may cause.
- Proceed to acknowledge that you are voluntarily entering the property despite the aforementioned risks. This will require an affirmative statement indicating your desire to proceed.
- Read and confirm your understanding of the release of liability clause. This section releases the Seller and their agents from any responsibility for injuries or damages related to the property.
- In this section, you will confirm your voluntary assumption of all risks associated with entering the property. This includes both known and unknown risks.
- Lastly, ensure that you sign and date the form for all parties involved. This confirms that all individuals listed have read and understood the terms set forth in the disclosure and release.
- After filling out all necessary sections, review the form for any errors. Finally, save changes, download, print, or share the completed form as needed.
Complete your Fannie Mae Disclosure and Release form online today to ensure compliance and understanding of property conditions.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
May 26, 2022 — The Enterprises will publish their first public disclosure reports under...
Currently Fannie Mae's MBS are not registered, and any disclosure is voluntary—and as I...
Only "agency records" that already exist are subject to FOIA's mandate of access. Agencies...
Get answers to your most pressing questions about US Legal Forms API.
What is the 5% rule for Fannie Mae?
The 5% rule for Fannie Mae indicates that if a borrower is financing a home with a down payment of less than 20%, they must have private mortgage insurance (PMI). This insurance protects the lender in case of default, ensuring added security for the investment. Understanding this rule can be essential for managing your mortgage obligations effectively. By becoming familiar with the Fannie Mae Disclosure and Release, you can better navigate these requirements.
What does it mean to release a security?
To release a security means that the lender relinquishes their interest or claim on the property securing the mortgage. It indicates that the borrower has met all their payment requirements, and the lender no longer holds rights to the property. This process is crucial for both parties, ensuring the borrower enjoys complete ownership of their home. Familiarizing yourself with the Fannie Mae Disclosure and Release can enhance your understanding of this procedure.
Why would a condo not be Fannie Mae approved?
A condo may not be Fannie Mae approved for several reasons. Often, it can be due to the condo association's financial health or if the development does not meet Fannie Mae's guidelines. Issues like excessive commercial space or inadequate reserve funds can also factor into this decision. Understanding the Fannie Mae Disclosure and Release process can help you navigate these challenges.
Why did my bank sell my mortgage to Fannie Mae?
Your bank likely sold your mortgage to Fannie Mae to manage their lending risks and ensure they have sufficient capital for future loans. This practice is common and helps maintain the overall health of the financial system. By understanding this process, you can better appreciate the stability that comes with the Fannie Mae Disclosure and Release.
Why did my mortgage get sold to Fannie Mae?
Your mortgage may have been sold to Fannie Mae to improve liquidity and portfolio management for your lender. This is a common practice in the mortgage industry, as it helps banks manage risk and continue lending. It is important to note that as a borrower, you still maintain your obligations, and these transactions often come with the advantages of the Fannie Mae Disclosure and Release to enhance your borrowing experience.
What is the difference between FNMA and FMAC?
FNMA, or Fannie Mae, is a government-sponsored enterprise focused on increasing homeownership, while FMAC, or Freddie Mac, operates with similar goals but is a separate entity. Both institutions provide vital liquidity to the mortgage market, but they differ in their specific programs and structures. Understanding these differences can help you navigate your mortgage options, especially in relation to the Fannie Mae Disclosure and Release.
What is Fannie Mae Dus?
Fannie Mae DUS, or Delegated Underwriting and Servicing, is a program that allows selected lenders to underwrite and service multifamily loans. It streamlines the lending process, enabling quicker decisions and fund availability. Through Fannie Mae Disclosure and Release, borrowers can enjoy seamless transitions and enhanced support throughout their mortgage experience.
Is it bad if Fannie Mae buys your mortgage?
No, it is not necessarily bad if Fannie Mae buys your mortgage. In fact, this can often be a positive change. It means your mortgage may be more secure, as Fannie Mae is a well-established institution that helps stabilize the housing market. Additionally, you can benefit from better terms and services as a result of the Fannie Mae Disclosure and Release process.
What is the purpose of Freddie Mac and Fannie Mae?
Fannie Mae and Freddie Mac were created by Congress. They perform an important role in the nation's housing finance system – to provide liquidity, stability and affordability to the mortgage market.
What are the disadvantages of a Fannie Mae loan?
Although Fannie Mae loans offer a low down payment option of 3%, if your down payment is not equal to a certain amount, you'll need to purchase mortgage insurance. This extra monthly cost is added to your mortgage.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.