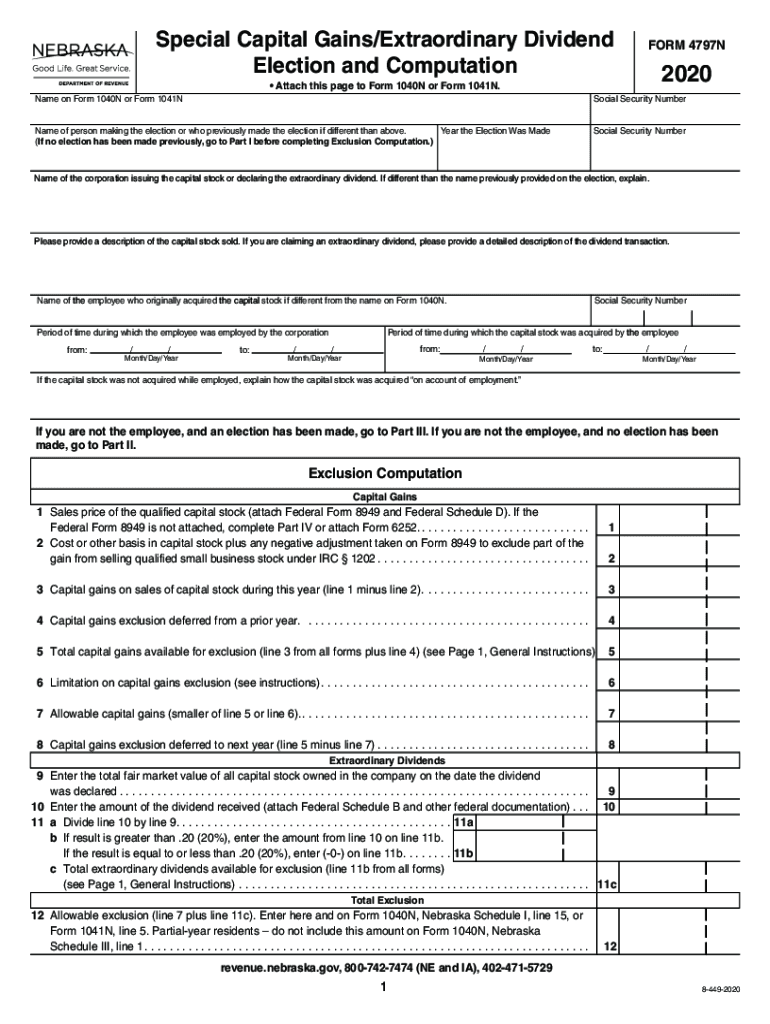
PRINTRESETSpecial Capital Gains/Extraordinary Dividend Election and ComputationFORM 4797N2020 Attach this page to Form 1040N or Form 1041N. Name on Form 1040N or Form 1041NSocial Security NumberName.

Open form follow the instructions

Easily sign the form with your finger

Send filled & signed form or save
How to fill out the NE DoR 4797N online
Filling out the NE DoR 4797N form online is an important step for individuals making a special capital gains or extraordinary dividend election in Nebraska. This guide provides clear and concise instructions to assist users in accurately completing each section of the form, ensuring a smooth filing process.
Follow the steps to effectively complete the NE DoR 4797N online.
- Press the ‘Get Form’ button to access the NE DoR 4797N form and open it for editing.
- Begin by entering your name as it appears on Form 1040N or Form 1041N, followed by your social security number.
- If the person making the election differs from the name listed previously, provide their name and social security number as well as the year the election was made.
- Specify the name of the corporation that issued the capital stock or declared the extraordinary dividend, along with an explanation if this differs from previous entries.
- Provide detailed descriptions of the capital stock sold or the extraordinary dividend transaction.
- Begin the computation section. Enter the sales price of the qualified capital stock as advised on Federal Form 8949 or Federal Schedule D, and attach these forms if applicable.
- List the cost or other basis of the capital stock, taking into account any negative adjustments noted on Form 8949.
- Calculate the capital gains on the sale of capital stock during the year by subtracting the cost from the sales price.
- If applicable, input any capital gains exclusion deferred from a prior year.
- Total the capital gains available for exclusion and note any limitations imposed.
- Record any extraordinary dividends received, ensuring these are documented properly, and calculate total extraordinary dividends available for exclusion.
- Finally, sum the allowable exclusion and prepare to save changes, download, print, or share the completed form.
Start filling out the NE DoR 4797N online today to complete your form accurately and efficiently.
Experience a faster way to fill out and sign forms on the web. Access the most extensive library of templates available.
Related content
the Nebraska Department of Revenue (DOR) if you have a specific question ... election was...
n.e i .i-;u? rt 111l'3 3 i r"--1 oa la r3 n L, C rri nt a rr, i, aTLI l .:r. ia ,: :c'"...
Get answers to your most pressing questions about US Legal Forms API.
What is the Nebraska state capital gains tax rate?
Nebraska Capital Gains Tax Long- and short-term capital gains are included as regular income on your Nebraska income tax return. That means they are taxed at the rates listed above (2.46% - 6.84%), depending on your total taxable income.
What is long term capital gains tax in Nebraska?
Nebraska Capital Gains Tax Long- and short-term capital gains are included as regular income on your Nebraska income tax return. That means they are taxed at the rates listed above (2.46% - 6.84%), depending on your total taxable income.
What is Nebraska capital gain exclusion?
Nebraska's special capital gains exclusion was adopted in 1987 as part of the Employment and Investment Growth Act. This allows individual taxpayers to make a one-time election to exclude Nebraska income capital gains from the sale of the stock of a qualified corporation.
What is an extraordinary dividend in a trust?
Generally, a dividend is deemed "extraordinary" for purposes of IRC § 1059 when it exceeds 10 percent (five percent in the case of preferred stock) of a corporate taxpayer's adjusted basis in a share of stock.
What is Form 4797N?
The Form 4797N must be completed each consecutive year until the prior year carryover has been used. If your federal capital loss is less than $3,000, the available carryover must be used. The carryover amount must be used or forfeited each year, unless the taxpayer has a negative adjusted taxable income for the year.
What is Nebraska special capital gain exclusion?
Nebraska's special capital gains exclusion was adopted in 1987 as part of the Employment and Investment Growth Act. This allows individual taxpayers to make a one-time election to exclude Nebraska income capital gains from the sale of the stock of a qualified corporation.
Does Ohio have capital gains tax?
Capital gains are taxable at both the federal and state levels.
Use professional pre-built templates to fill in and sign documents online faster. Get access to thousands of forms.
If you believe that this page should be taken down, please follow our DMCA take down process here.