Arizona Lease with Option to Purchase - Lease or Rent to Own
Overview of this form
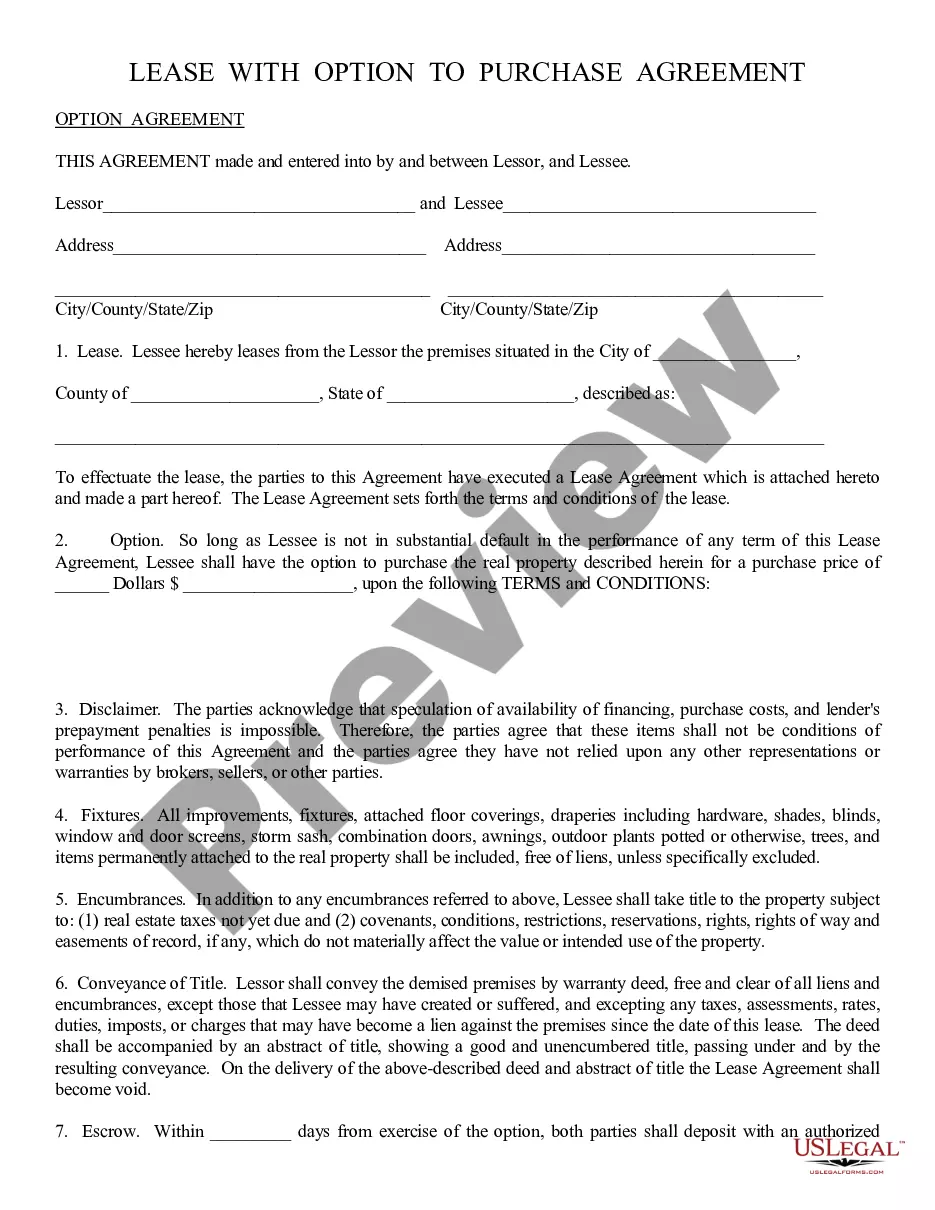
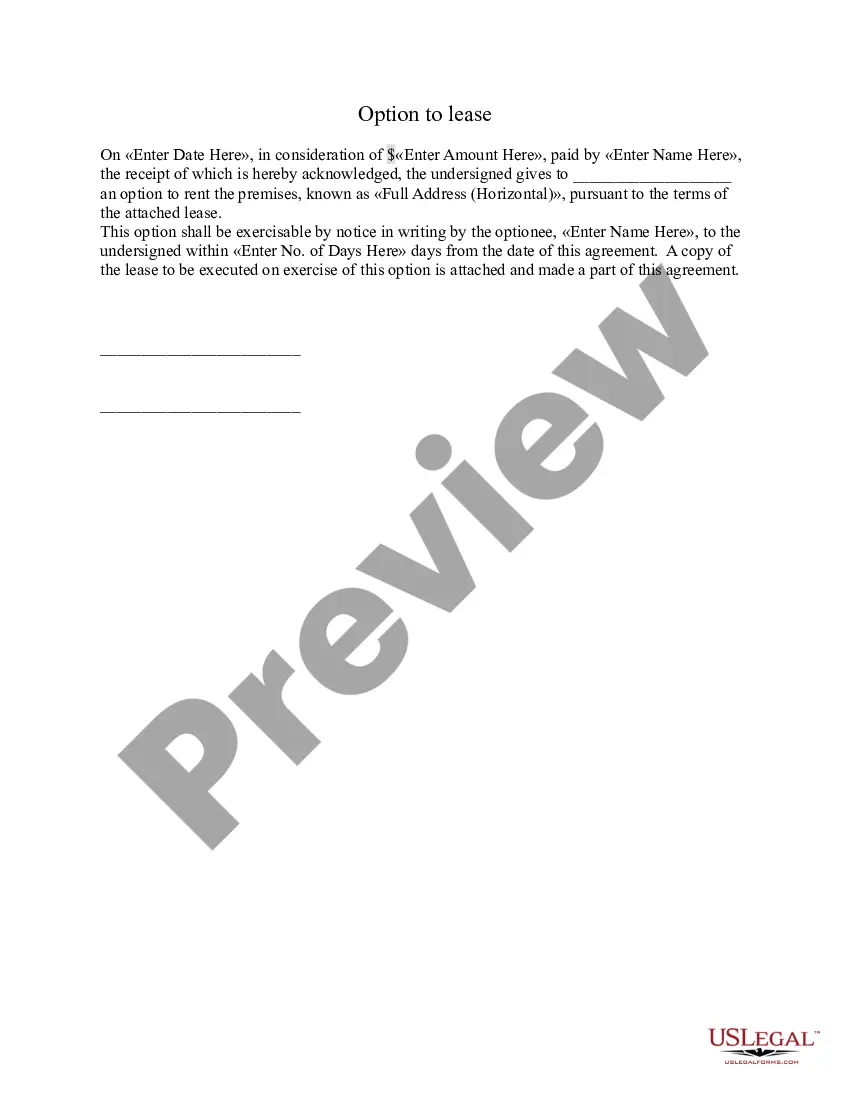
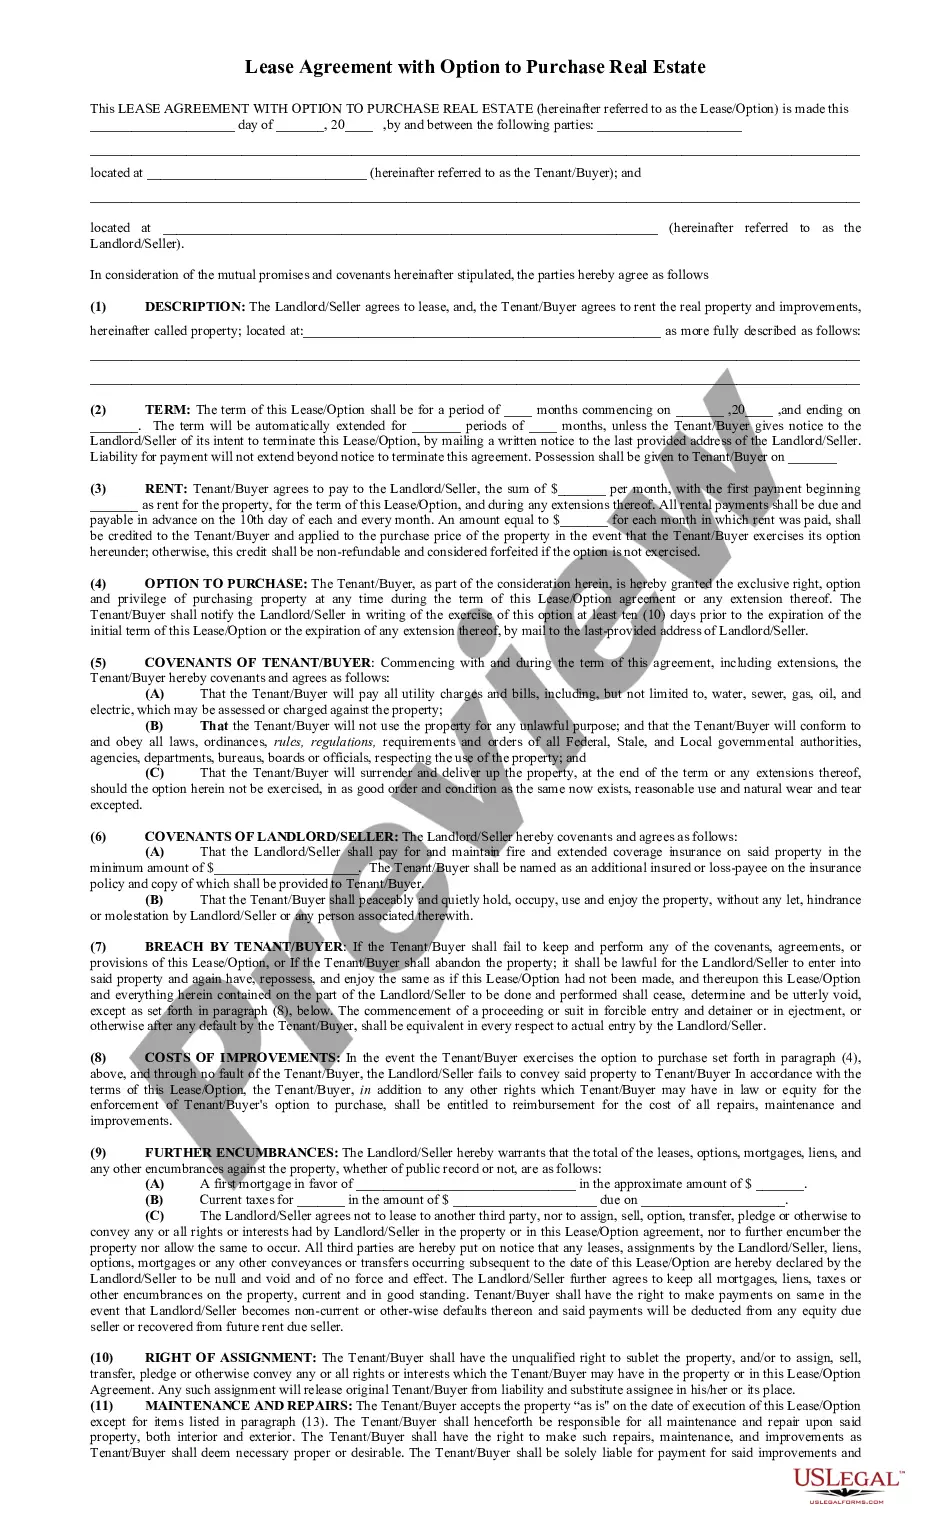
The Lease with Option to Purchase is a legal agreement that allows a tenant (lessee) to rent a property with a potential purchase option at a later date. This form differs from standard lease agreements by incorporating terms that outline the possibility of buying the property at a predetermined price. This arrangement is commonly referred to as a rent-to-own agreement and provides tenants with the opportunity to become homeowners while first leasing the property they intend to buy.
Main sections of this form
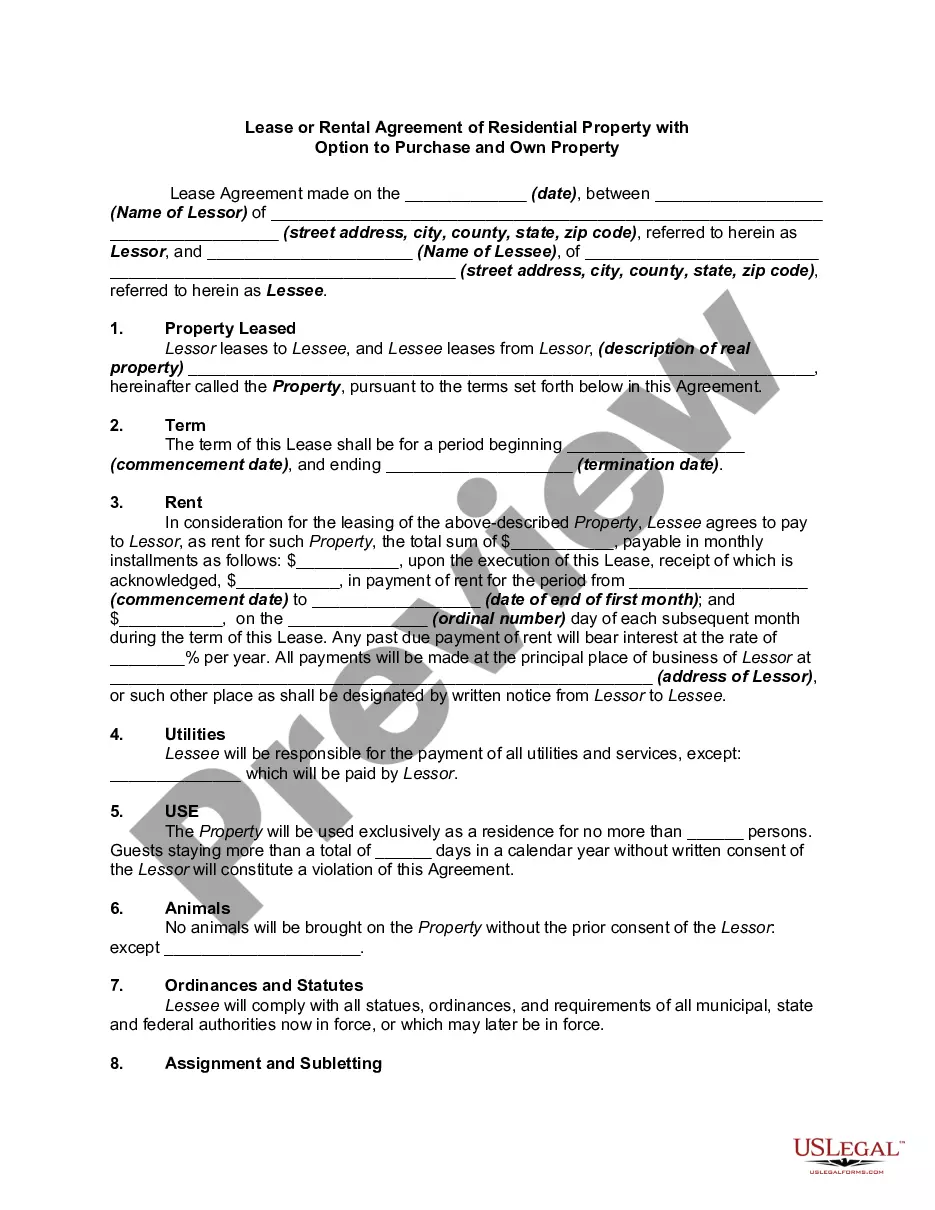
- Lease Agreement: Outlines the standard rental terms between the lessor and lessee.
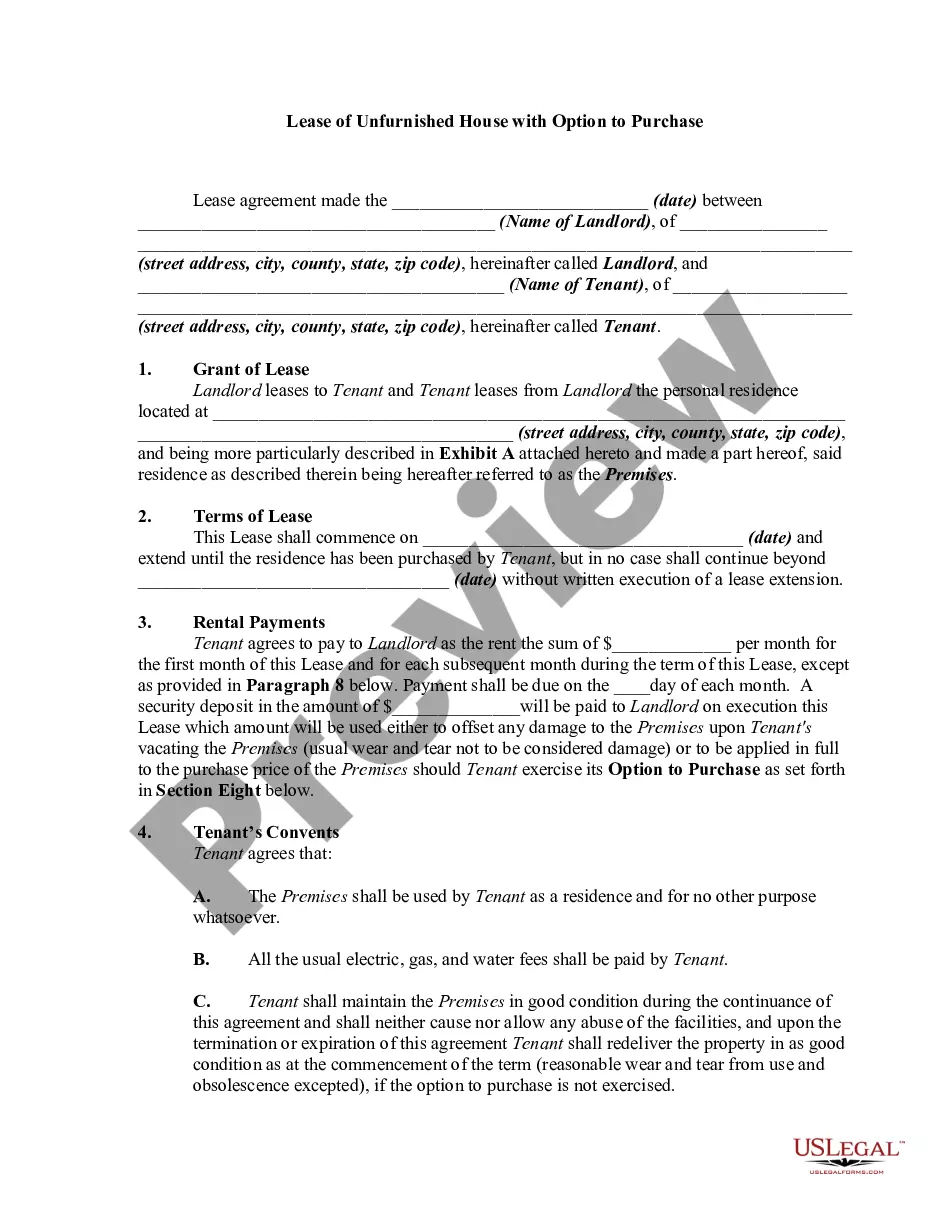
- Option to Purchase: Defines the terms under which the lessee can buy the property after the lease period.
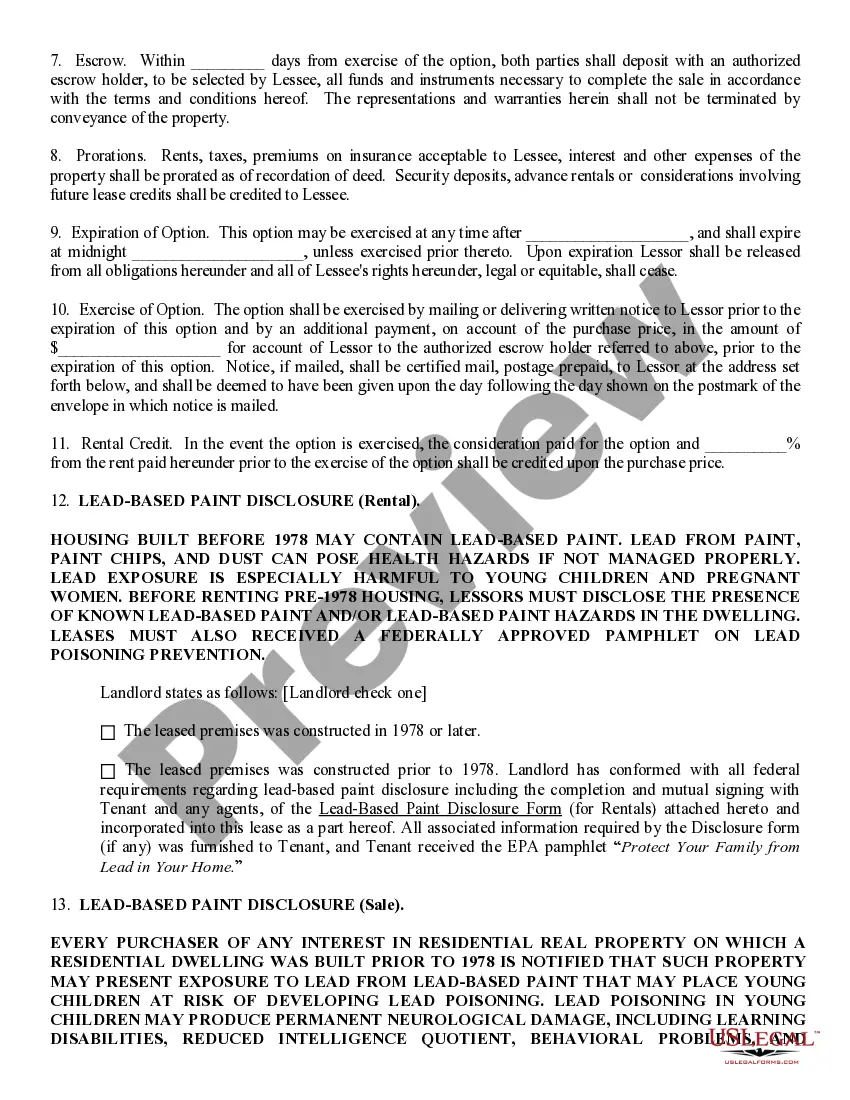
- Fixtures and Improvements: Specifies items included in the sale, such as appliances or permanent installations.
- Disclaimer: Clarifies that expectations around financing and costs are not guaranteed.
- Title Conveyance: Details the process for transferring ownership upon exercising the purchase option.
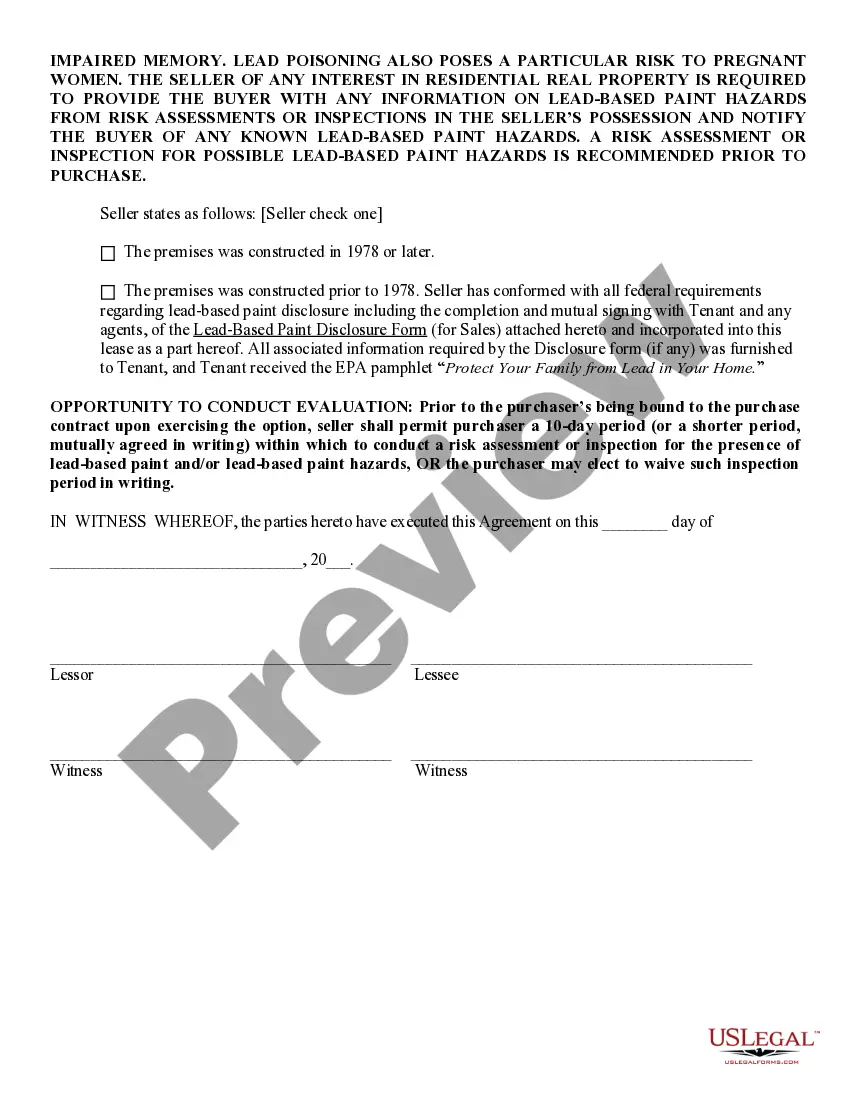
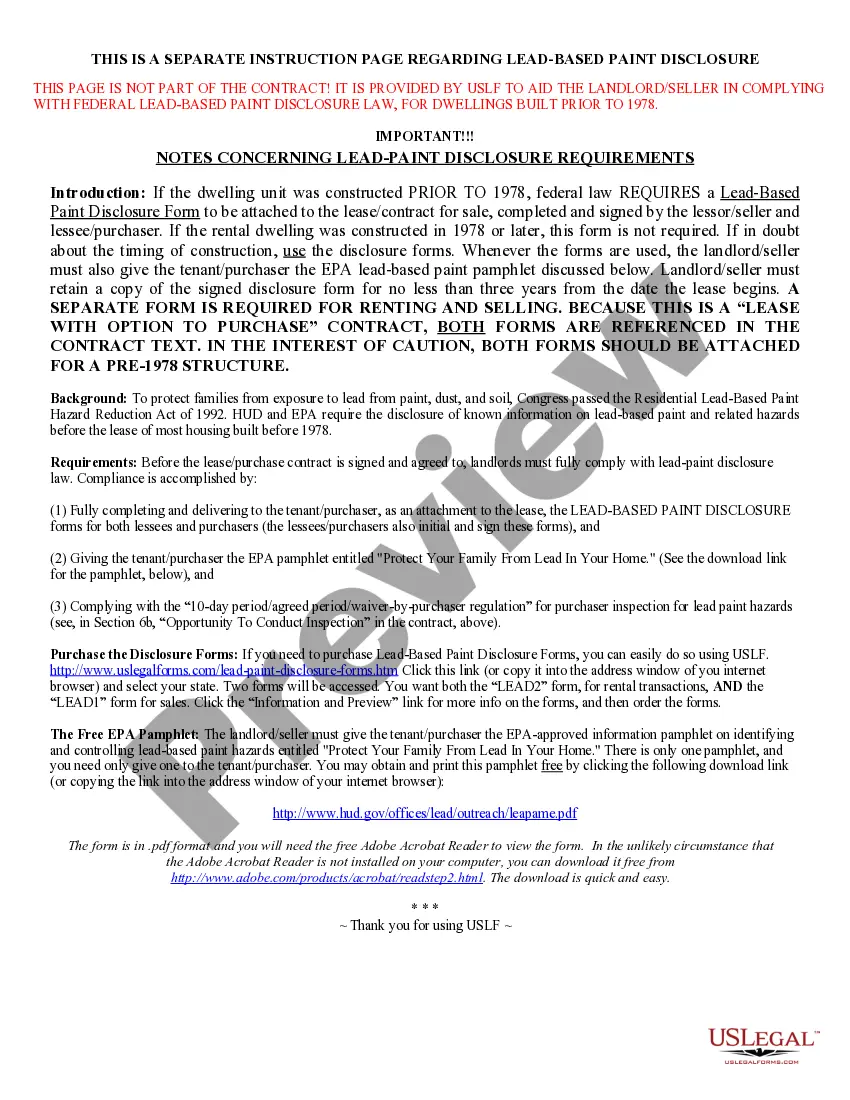
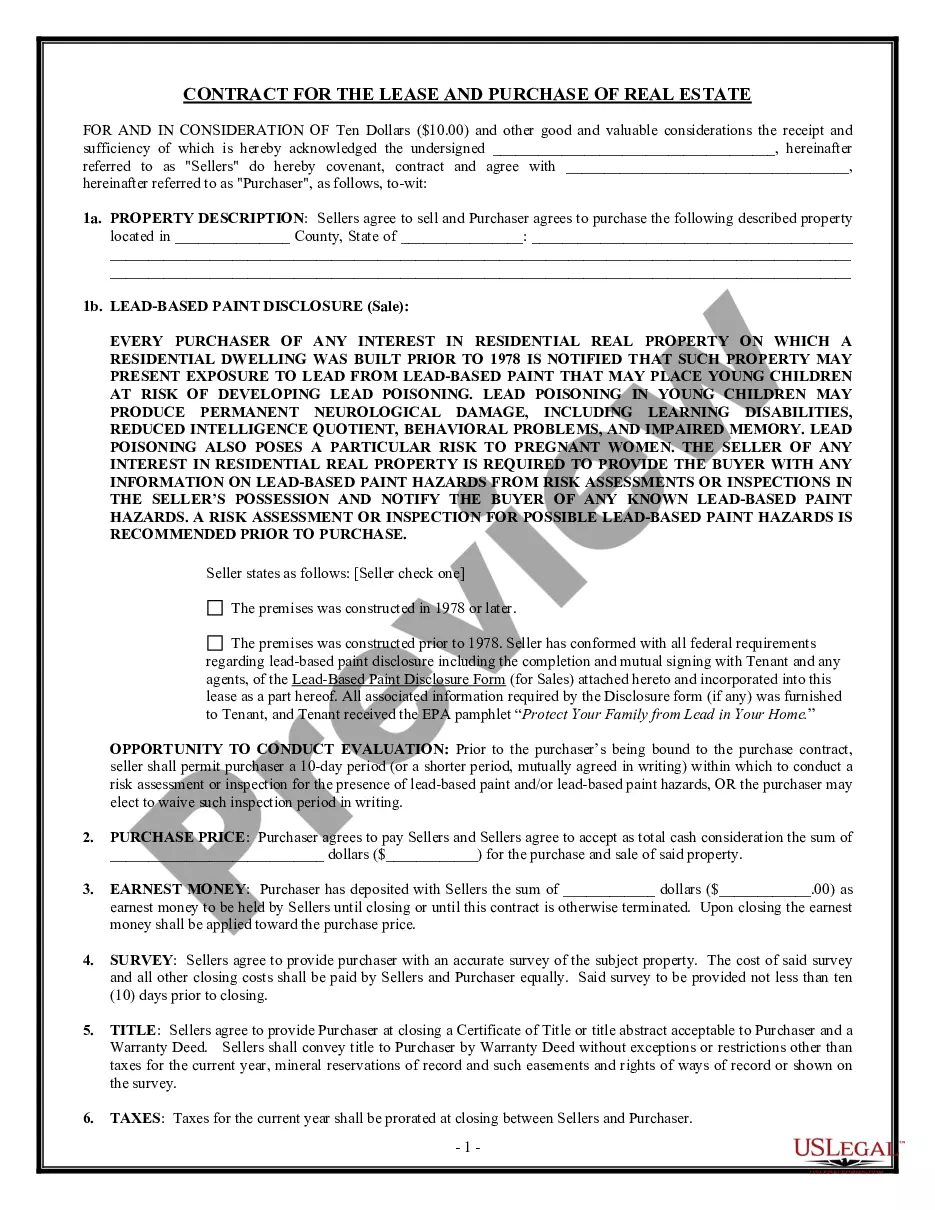
- Lead-Based Paint Disclosure: Ensures compliance with legal requirements regarding properties built before 1978.
Common use cases
This form is ideal when a prospective buyer wants to rent a home while keeping the option to purchase it later. It is particularly beneficial in situations where the buyer may need time to secure financing or improve their credit. Common scenarios include individuals who are not yet ready to commit to a full purchase, those wanting to try out a property before buying, or buyers looking for flexibility in uncertain financial conditions.
Who needs this form
- Tenants interested in a rent-to-own option to purchase a home.
- Landlords who want to attract tenants while providing them with a future purchase opportunity.
- Real estate investors looking to create flexible lease agreements.
- Individuals seeking to secure property without the immediate responsibilities of full ownership.
Steps to complete this form
- Identify the parties involved: Fill in the names and addresses of the lessor and lessee.
- Specify the property: Enter the exact address and description of the leased property.
- Outline the rental and purchase terms: Include the purchase price and any conditions relevant to the purchase option.
- Incorporate the Lead-Based Paint Disclosure: Complete and attach the necessary lead-based paint forms if applicable.
- Dates and signatures: Ensure both parties sign the document, noting the execution date.
Does this document require notarization?
To make this form legally binding, it must be notarized. Our online notarization service, powered by Notarize, lets you verify and sign documents remotely through an encrypted video session.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Neglecting to specify clear terms for the purchase option, leading to misunderstandings later.
- Failing to include necessary disclosures, such as the lead-based paint information for older properties.
- Not ensuring both parties sign the document, which could invalidate the agreement.
- Missing details about fixtures and improvements included in the sale.
Advantages of online completion
- Convenience: Download and complete the form easily from your home.
- Editability: Personalize the form according to your specific agreement and circumstances.
- Professionalism: Access professionally drafted forms that comply with legal standards.
- Secure storage: Keep your legal documents organized and accessible at all times.
Looking for another form?
Form popularity
FAQ
Rent-to-own homes come with a significant risk to buyers. If the owner of the property gets foreclosed on, you're going to be forced to leave. The contract with be forfeited, and you'll have to buy the home from the bank. You may be able to get approved for a home even with bad credit.
Rent-to-own programs can be attractive to buyers, especially those who expect to be in a stronger financial position within a few years. Some of the benefits include: Buy with bad credit: Buyers who cannot qualify for a home loan can start buying a house with a rent-to-own agreement.
Luckily, programs like USDA and Federal Housing Administration home buying programs help those with low credit scores buy a home. For instance, FHA loans require 580 credit score while the down payment requirement is 3.5%.
Yes, if you are eligible for a VA loan, you may be able to qualify with a 524 credit score. Can I get a jumbo loan with a 524 credit score?Most jumbo mortgage lenders require a borrower to have a credit score of at least 680. However, there are some non-prime jumbo lenders that go down to 580.
Generally speaking, to get maximum financing on typical new home purchases, applicants should have a credit score of 580 or better. Those with credit scores between 500 and 579 are, according the FHA guidelines, "limited to 90 percent LTV".
Rent-to-own programs can be attractive to buyers, especially those who expect to be in a stronger financial position within a few years. Some of the benefits include: Buy with bad credit: Buyers who cannot qualify for a home loan can start buying a house with a rent-to-own agreement.
Minimum Credit Score Needed: You'll need a minimum credit score of 580 to qualify for an FHA loan that requires a down payment of just 3.5%. There is no minimum FICO®Score, though, to qualify for an FHA loan that requires a down payment of 10% or more.
You must have a credit score of at least 580 on the FICO® scale to get that 3.5% down payment, though. If your score falls anywhere between 500 and 580, you'll need to make a down payment closer to 10%. Even with the credit score requirement, an FHA loan is one of the easiest federal programs to qualify for.
Queen Creek. About an hour's drive southeast of Phoenix, Queen Creek has the most affordable rent in our top 20. Here, tenants pay about 14% of their income toward rent, which on average is $982. However, only a small percentage of housing units, 18.9%, are available for renters.